 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
China's underlying final demand for crude and oil products (excluding changes in inventories) has been weaker than is suggested by its imports of crude oil. The government has used lower oil prices to accumulate strategic petroleum reserves (SPR). Commodities prices are at a risk from weaker China/EM demand going forward.
We continue to view the rally in equities and high-yield corporate bonds since February as a high-risk affair.
We discuss the technical and political problems with helicopter money, plus the near-term outlook for the euro area economy and markets.
Profits are bottoming but the outlook is lackluster, even if further dollar weakness provides a temporary boost.
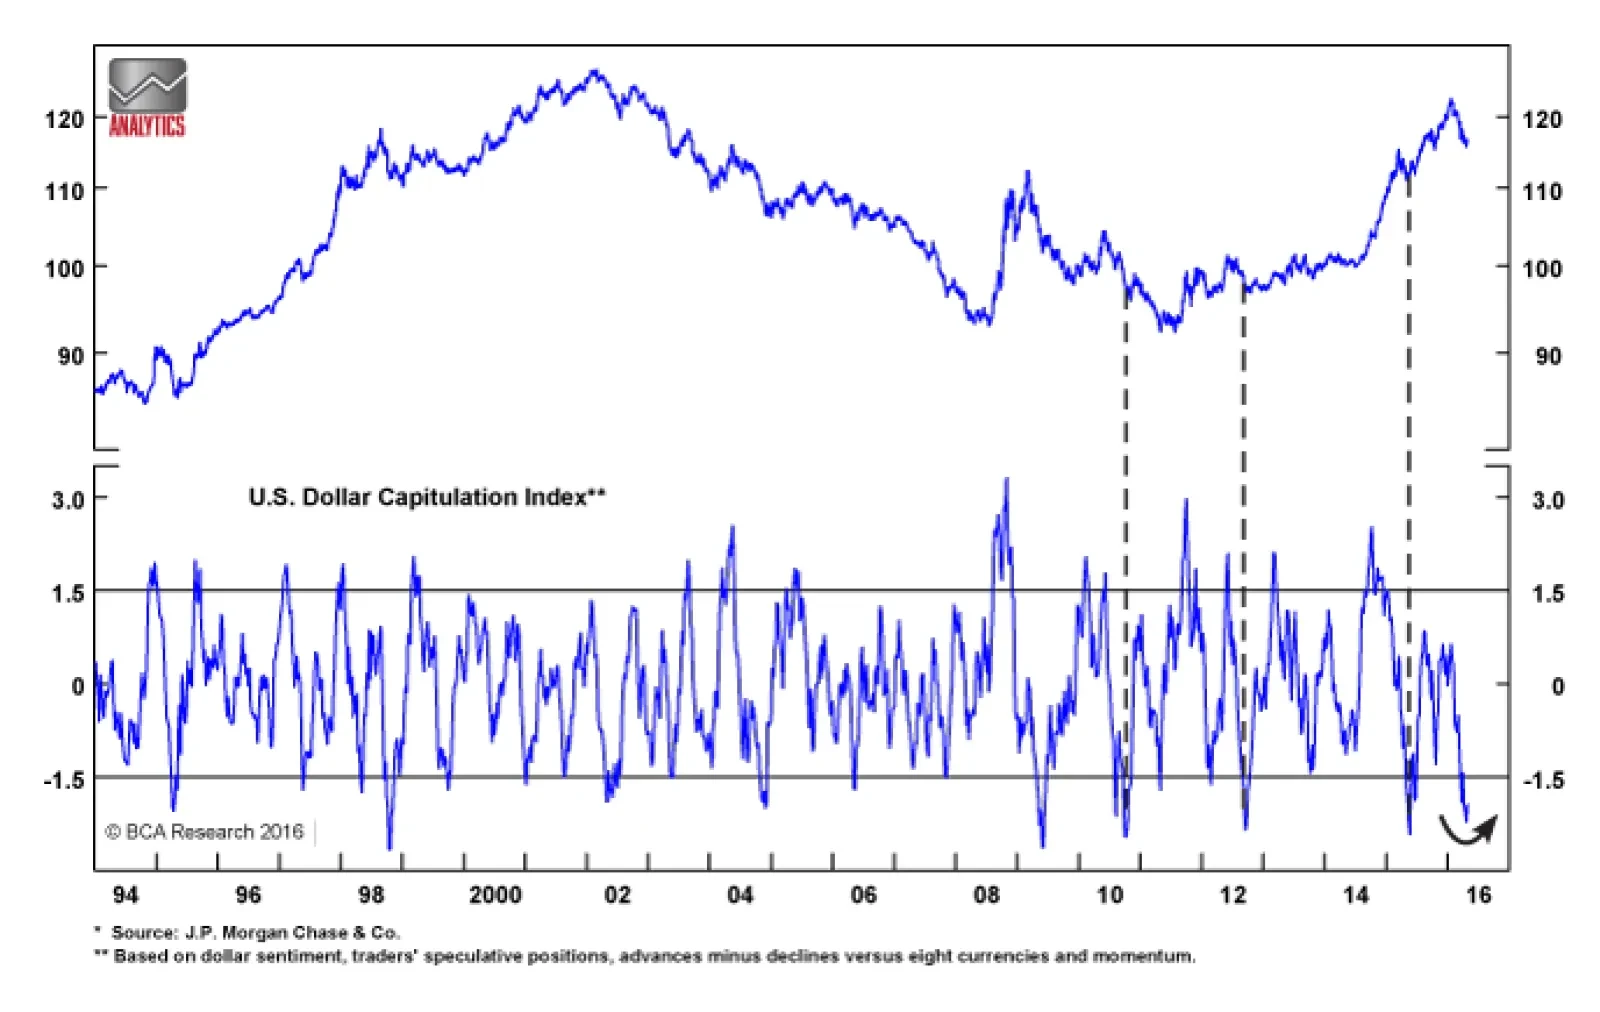
For the month of April, the model's performance was in line with the S&P 500, but lagged global equities. For May, the model is aggressively paring back its equity risk exposure. Both Europe and Emerging Markets were downgraded, but still possess the lion's share of the equity allocation, while defensive markets such as the U.S. and Switzerland received a boost. In the fixed-income space, U.S., Italian and Spanish paper were the model's favorites.
The Fed's statement underscored its 'go slow' approach, with a June hike increasingly unlikely, but September and December still in play. The BoJ stood pat, reluctant to admit that NIRP was a flop soon after it was launched. Nevertheless, we expect fresh easing this summer. Chinese stimulus should last a few more months, but commodities will resume their structural downtrend thereafter. Remain tactically bullish risk assets; be prepared to turn more cautious in Q2.