Latest from BCA Research
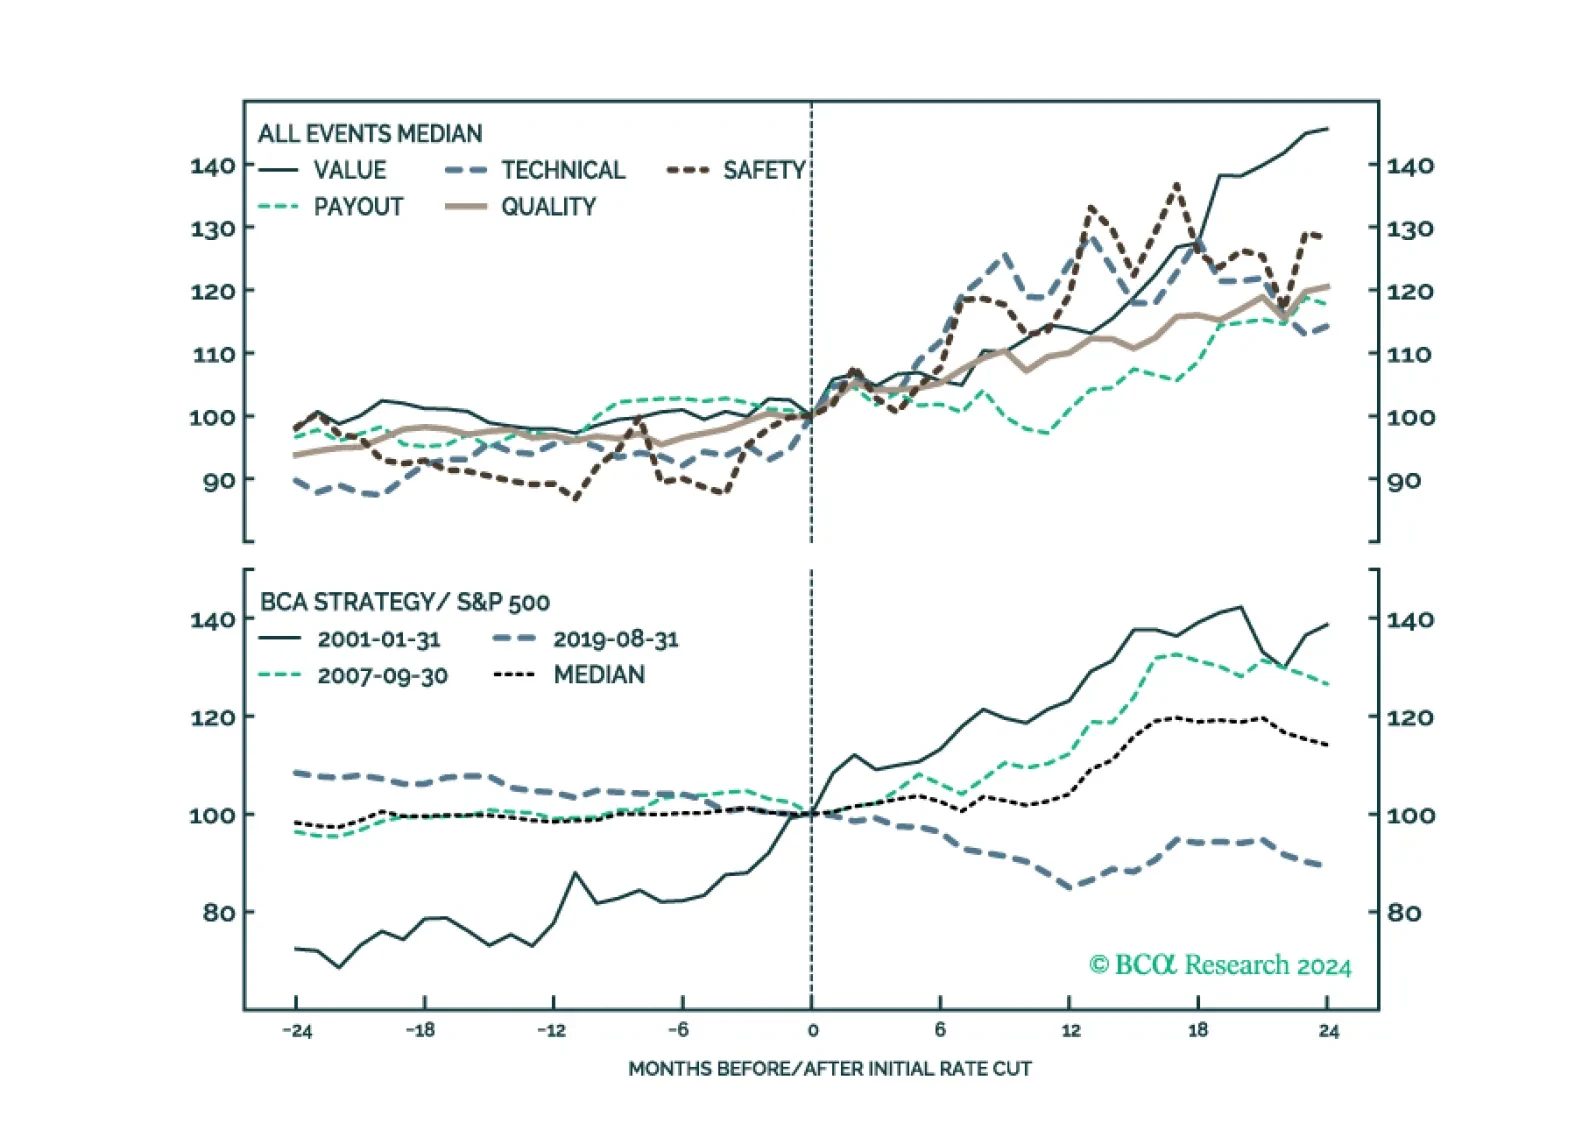
Initial rate cuts are not statistically significant for Equity Analyzer’s factors, though we still note Value and Safety as top performers. Sectors are the same. Defensives spike but lose traction as Cyclicals come into favor later. If a hard landing materializes as we expect, equities will move lower, even in the face of further rate cuts.
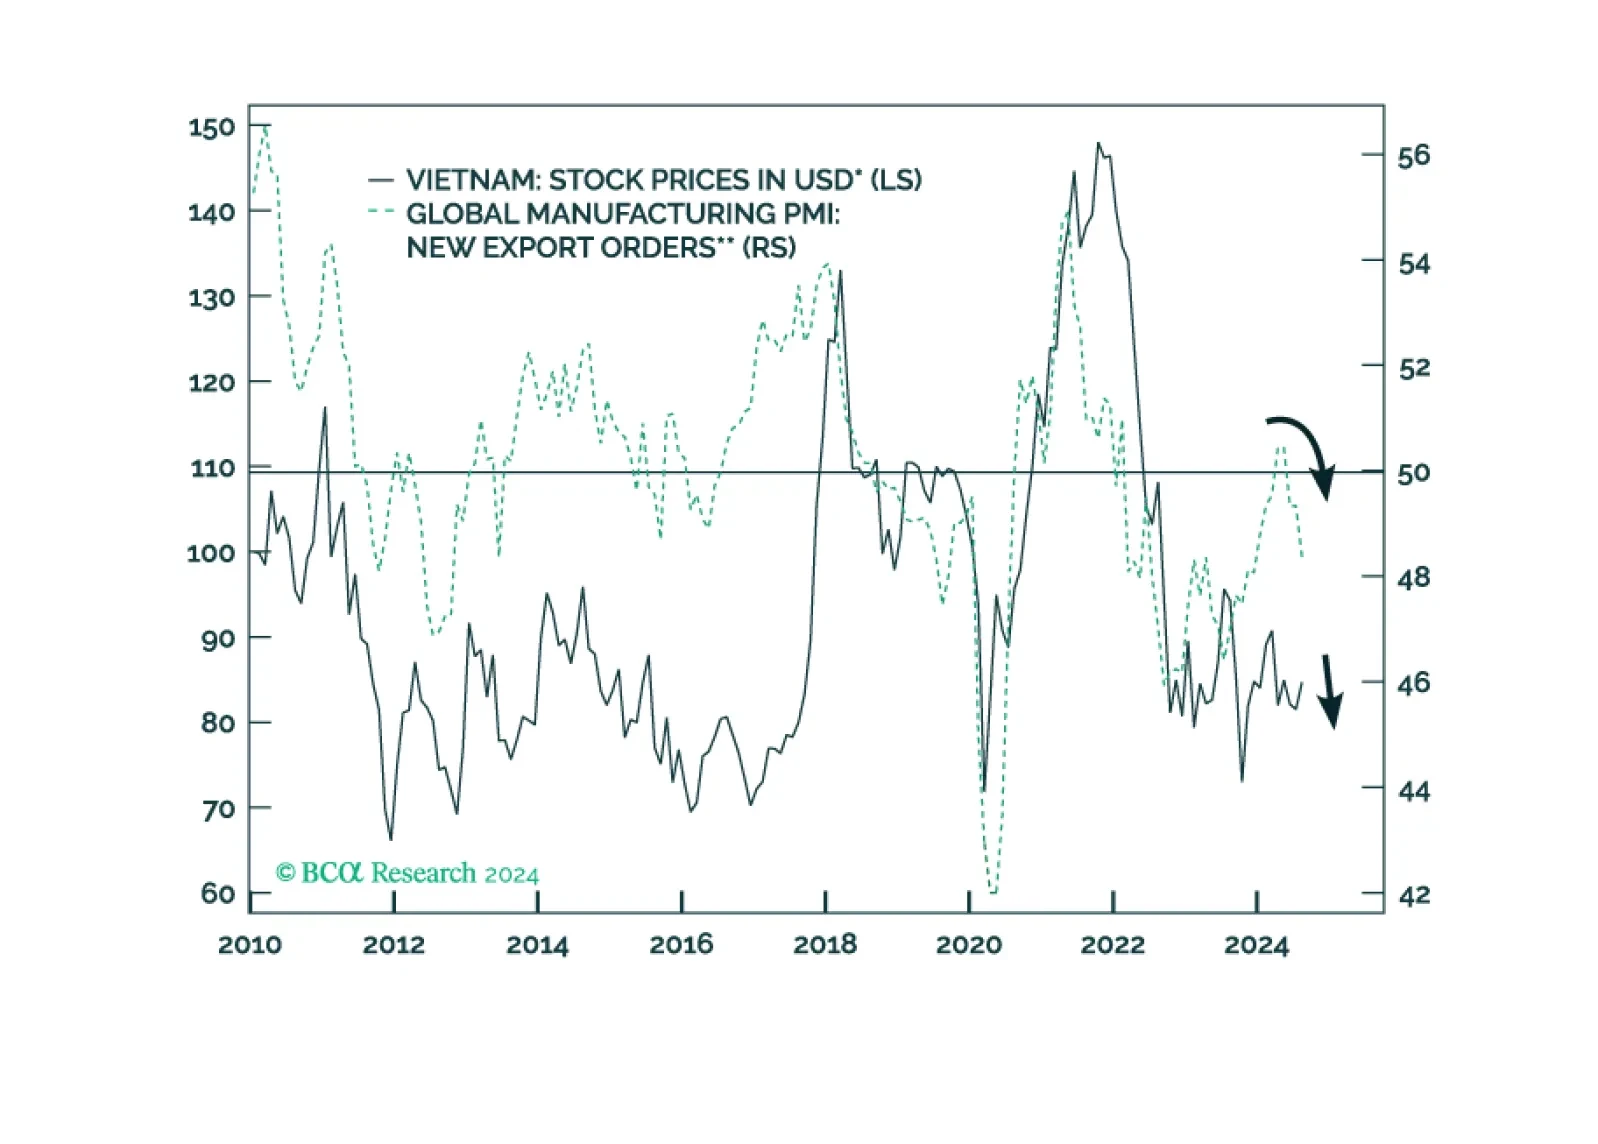
The Vietnamese economy is growing at a strong 7%. Why, then, are Vietnamese stocks struggling? Should investors expect a revival soon?
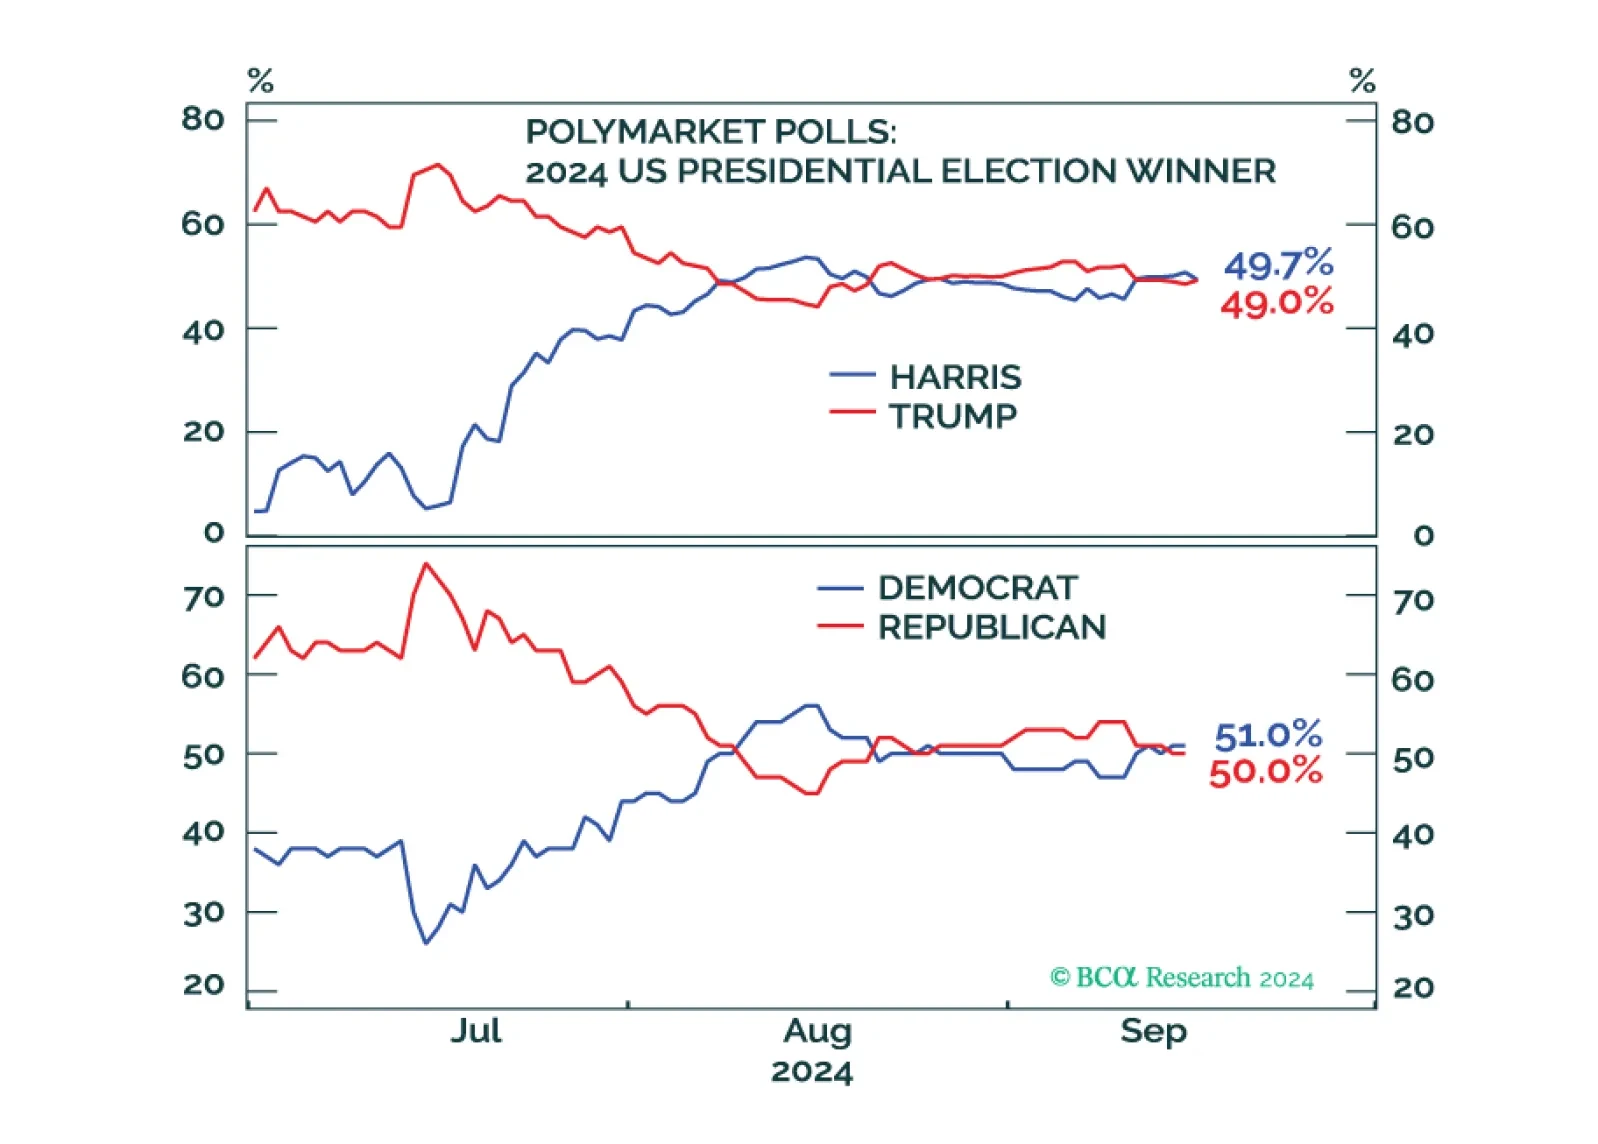
Investors should de-risk tactically in expectation of shocks and surprises ahead of the US election and an uncertain aftermath. Democratic victory with a gridlocked Congress is our base case but would bring minor tax hikes and nuclear brinksmanship with Russia. A Republican single-party sweep offers huge tax cuts but also a global trade war. Recession looms regardless.

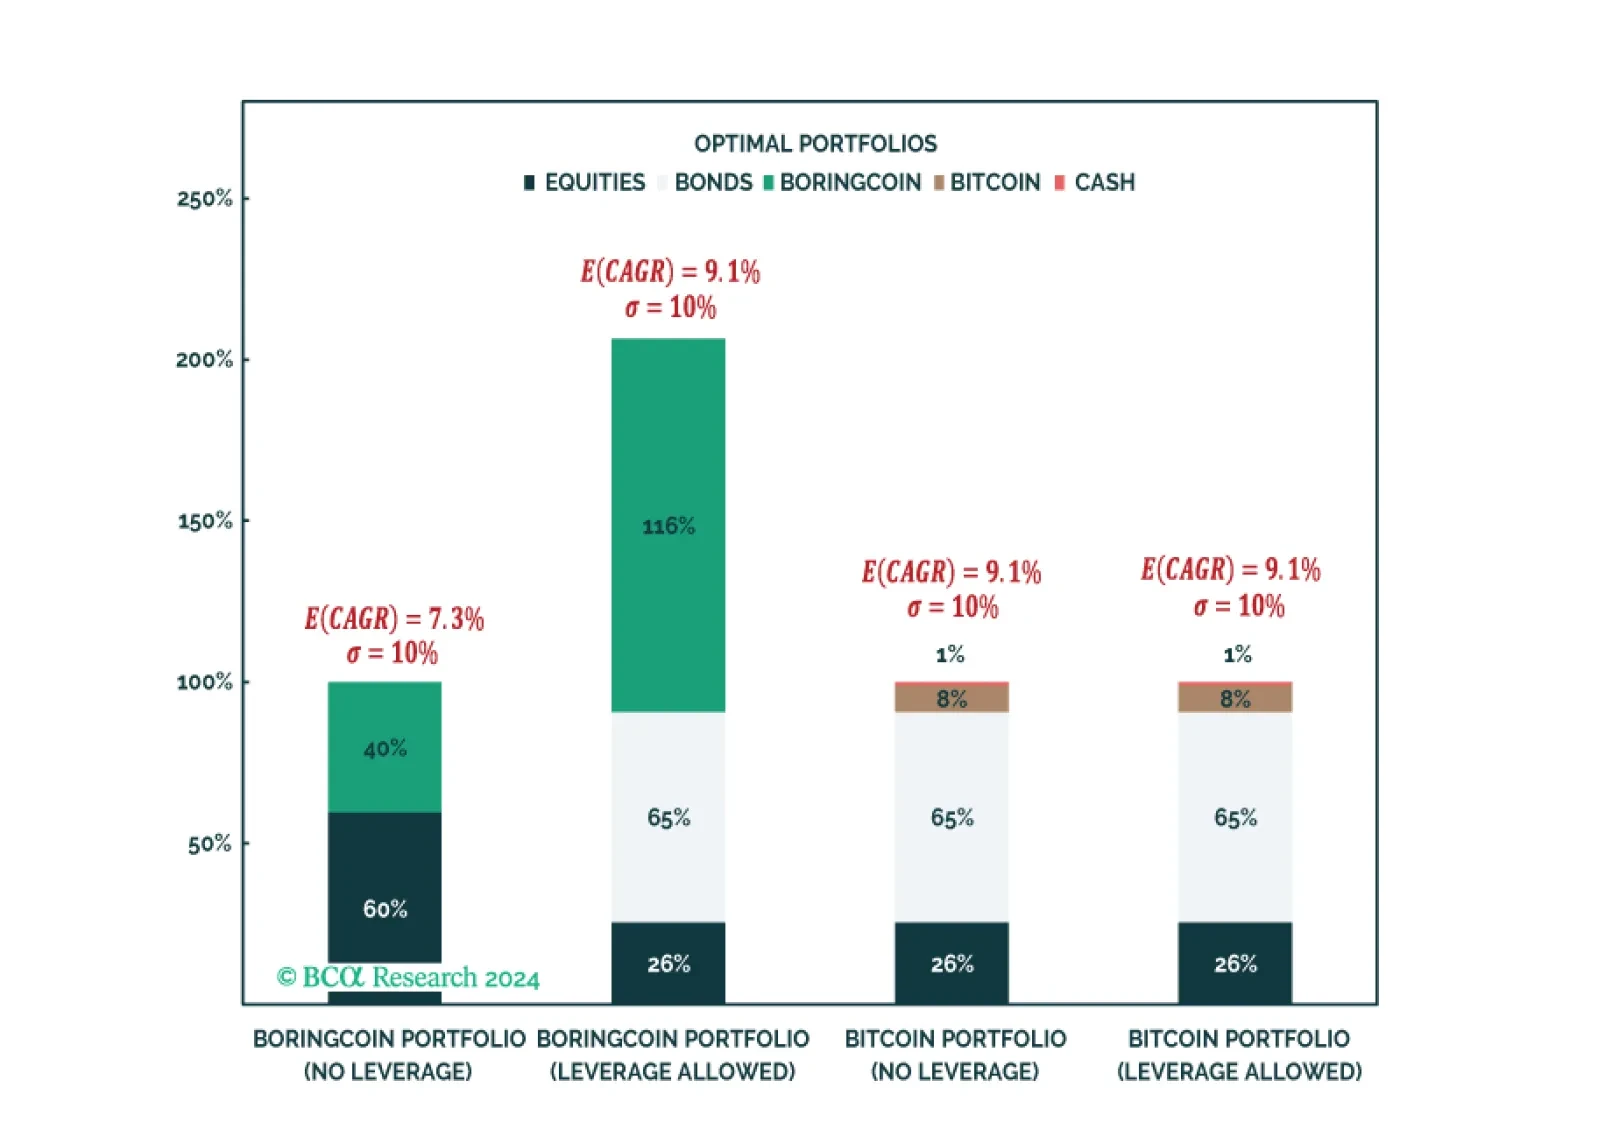
Conservative investors usually shy away from very volatile assets. But is this the right approach? By comparing Bitcoin with a hypothetical asset called “Boringcoin” we show that, all else being equal, high volatility assets are preferable as diversifiers due to better capital efficiency. Asset allocators should remember to think about their portfolio holistically and avoid looking at assets in isolation, particularly when they are very volatile.

A bearish chill has engulfed oil markets. Earlier this week, Brent dropped to a near three-year low, falling below the trading range that had prevailed over the prior 18 months. In this Strategy Insight we detail why we do not believe that the worst has passed for oil markets. Rather, prices are likely to drop further over a six-to-nine-month horizon.
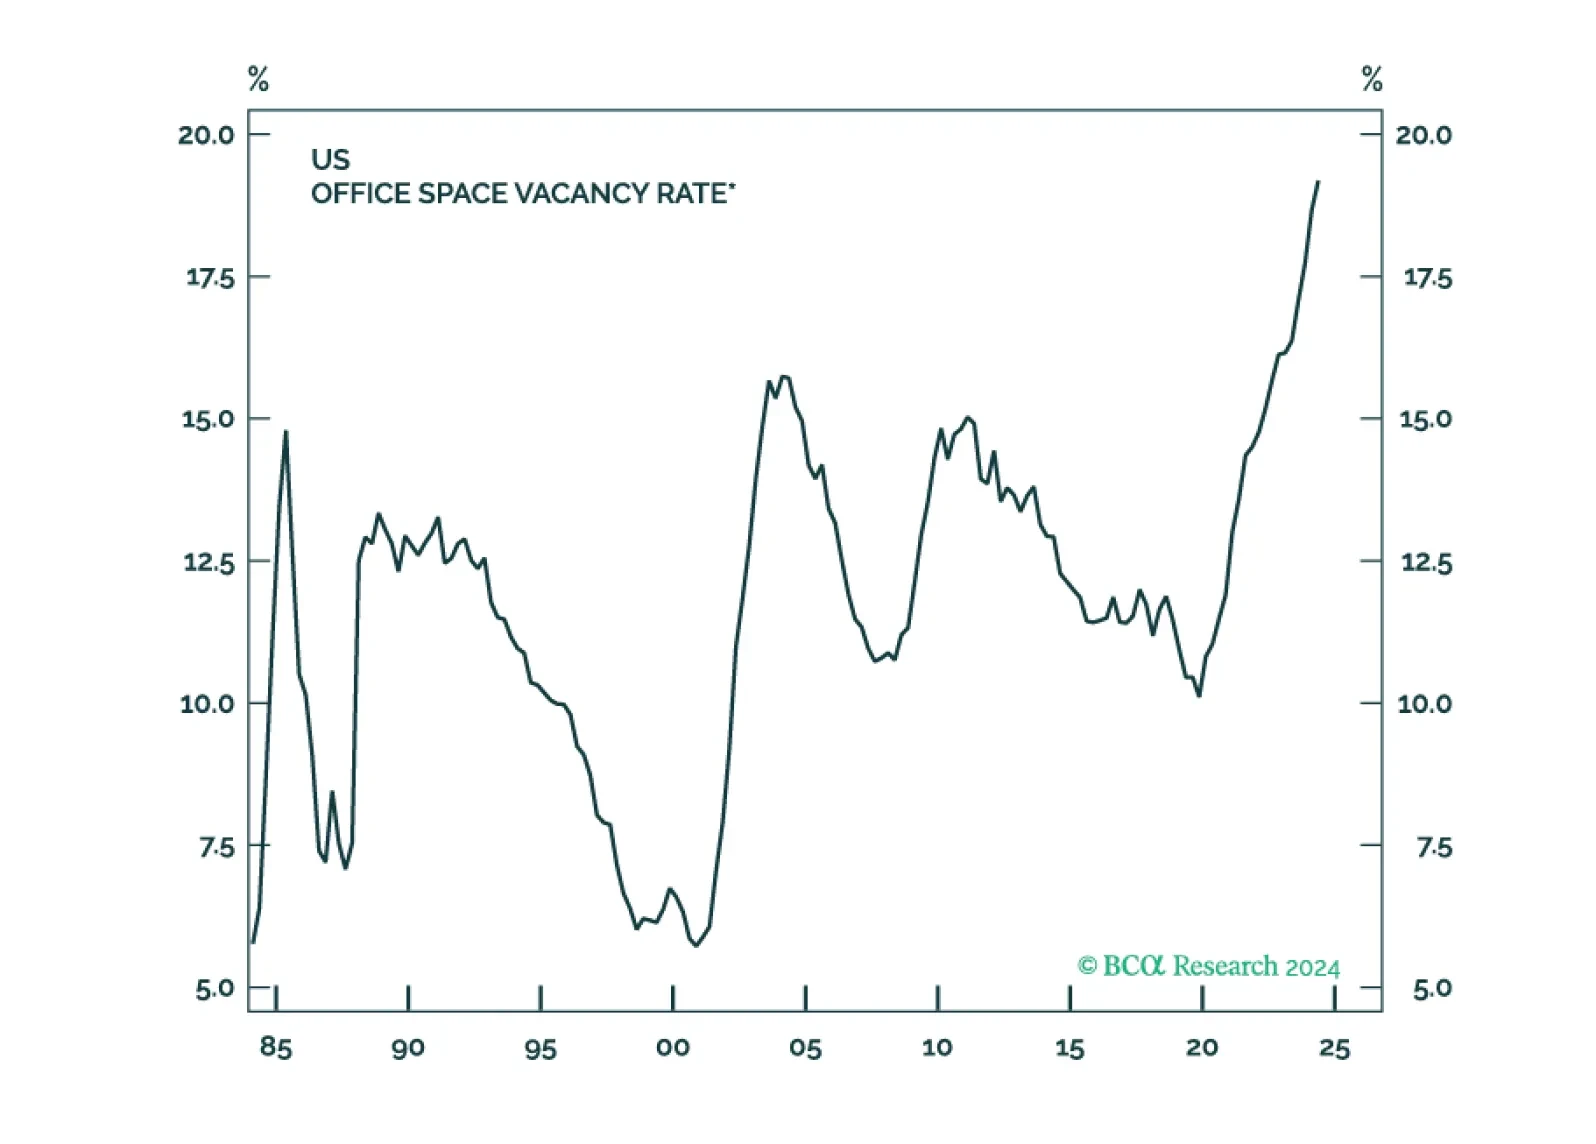
The US suffers from enough imbalances to produce a mild recession. Unfortunately, such a recession could lead to a significant bear market in stocks, just as it did during the very mild 2001 recession.
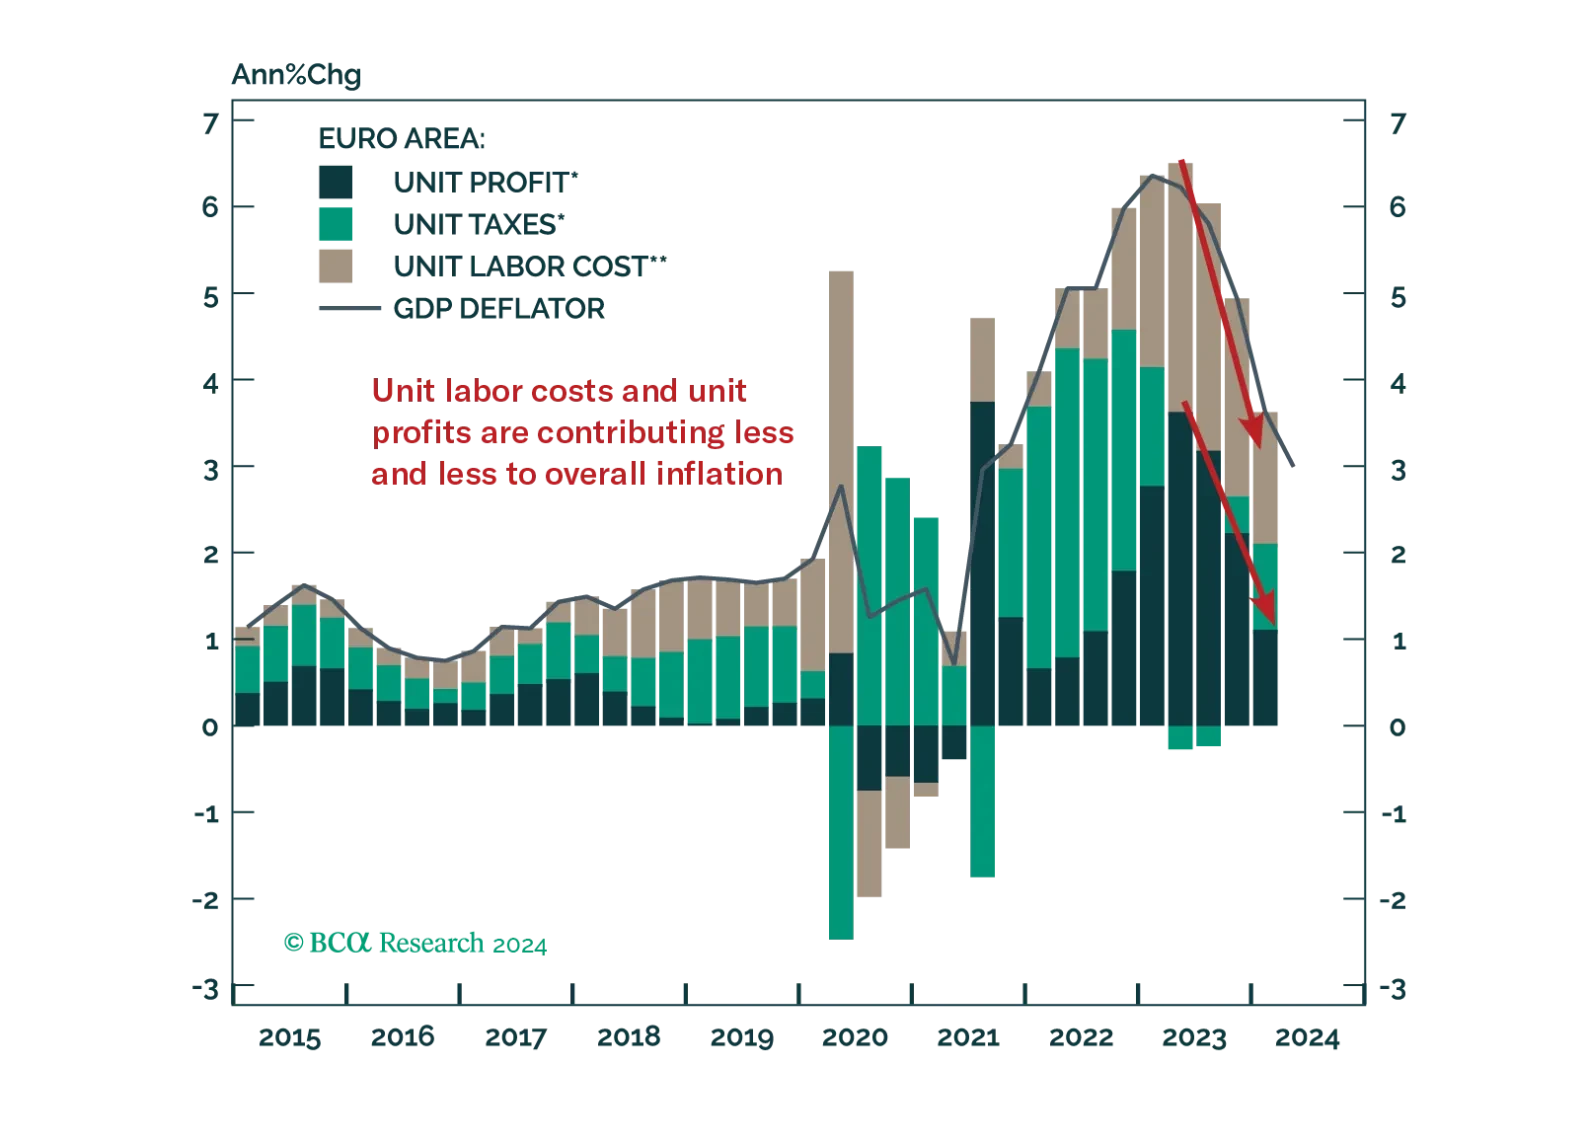
The ECB will cut rates once more this year; however, markets underprice how far it will ease next year.
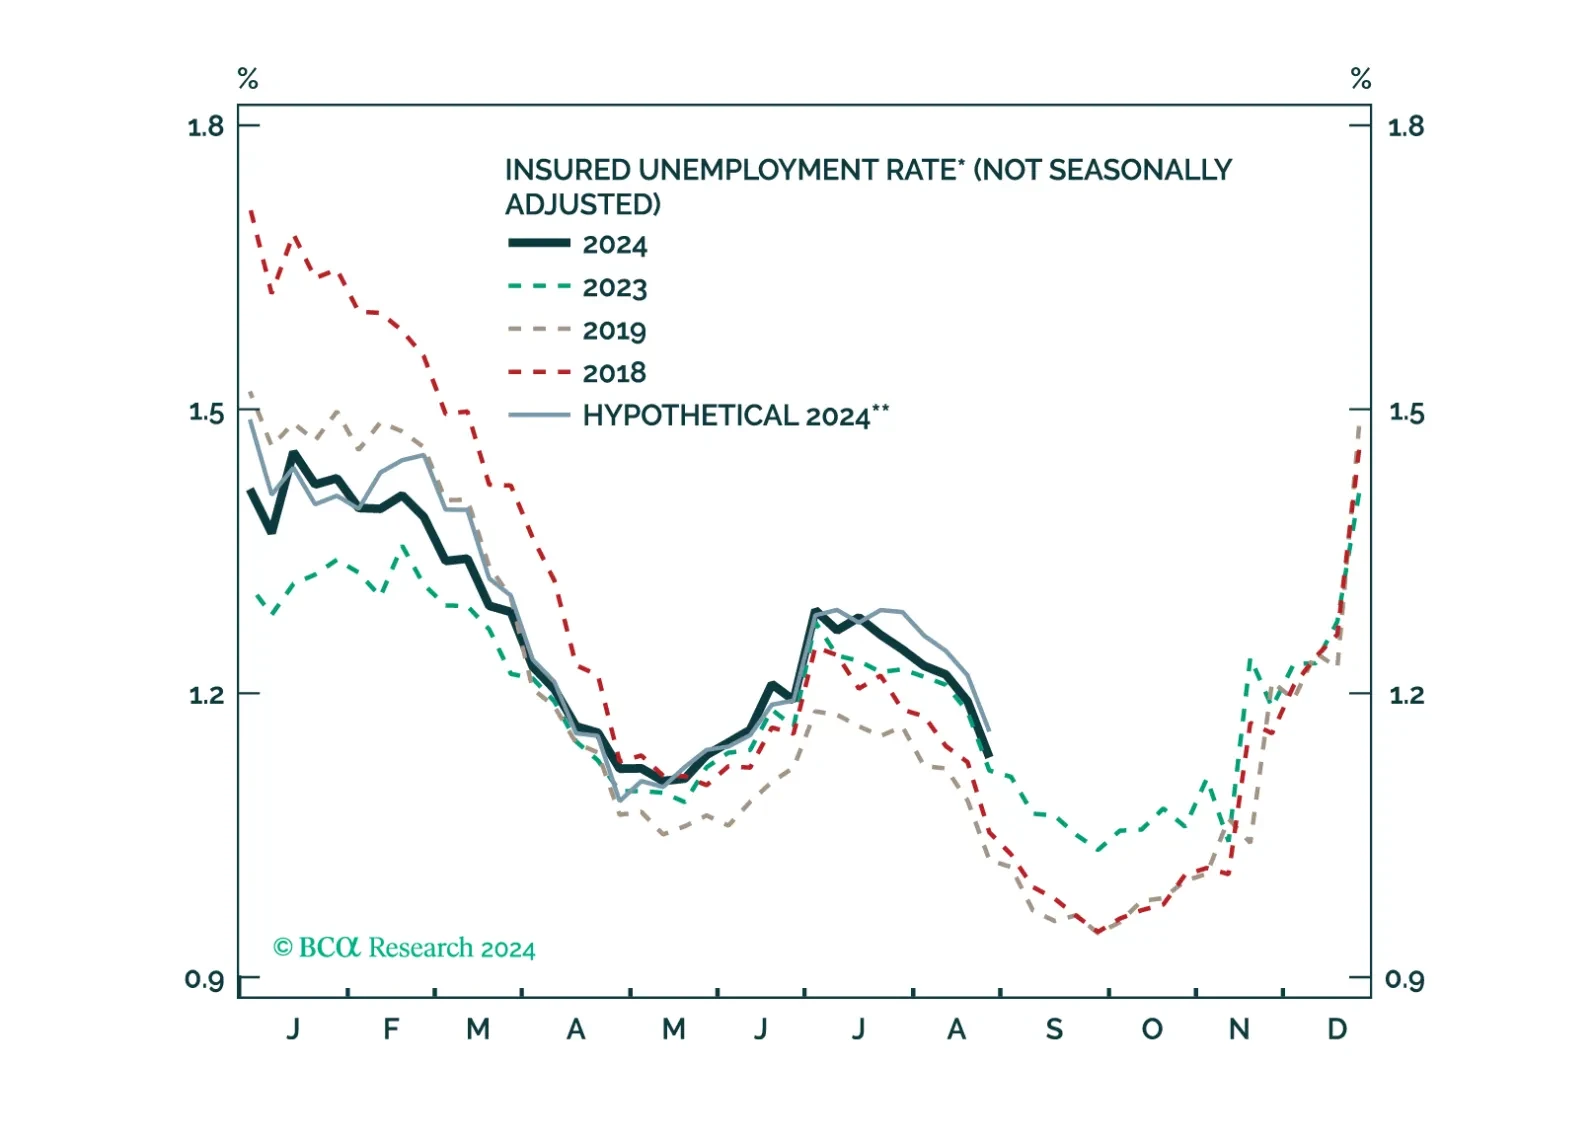
Some thoughts on this morning’s US claims report and a preview of next week’s FOMC meeting.
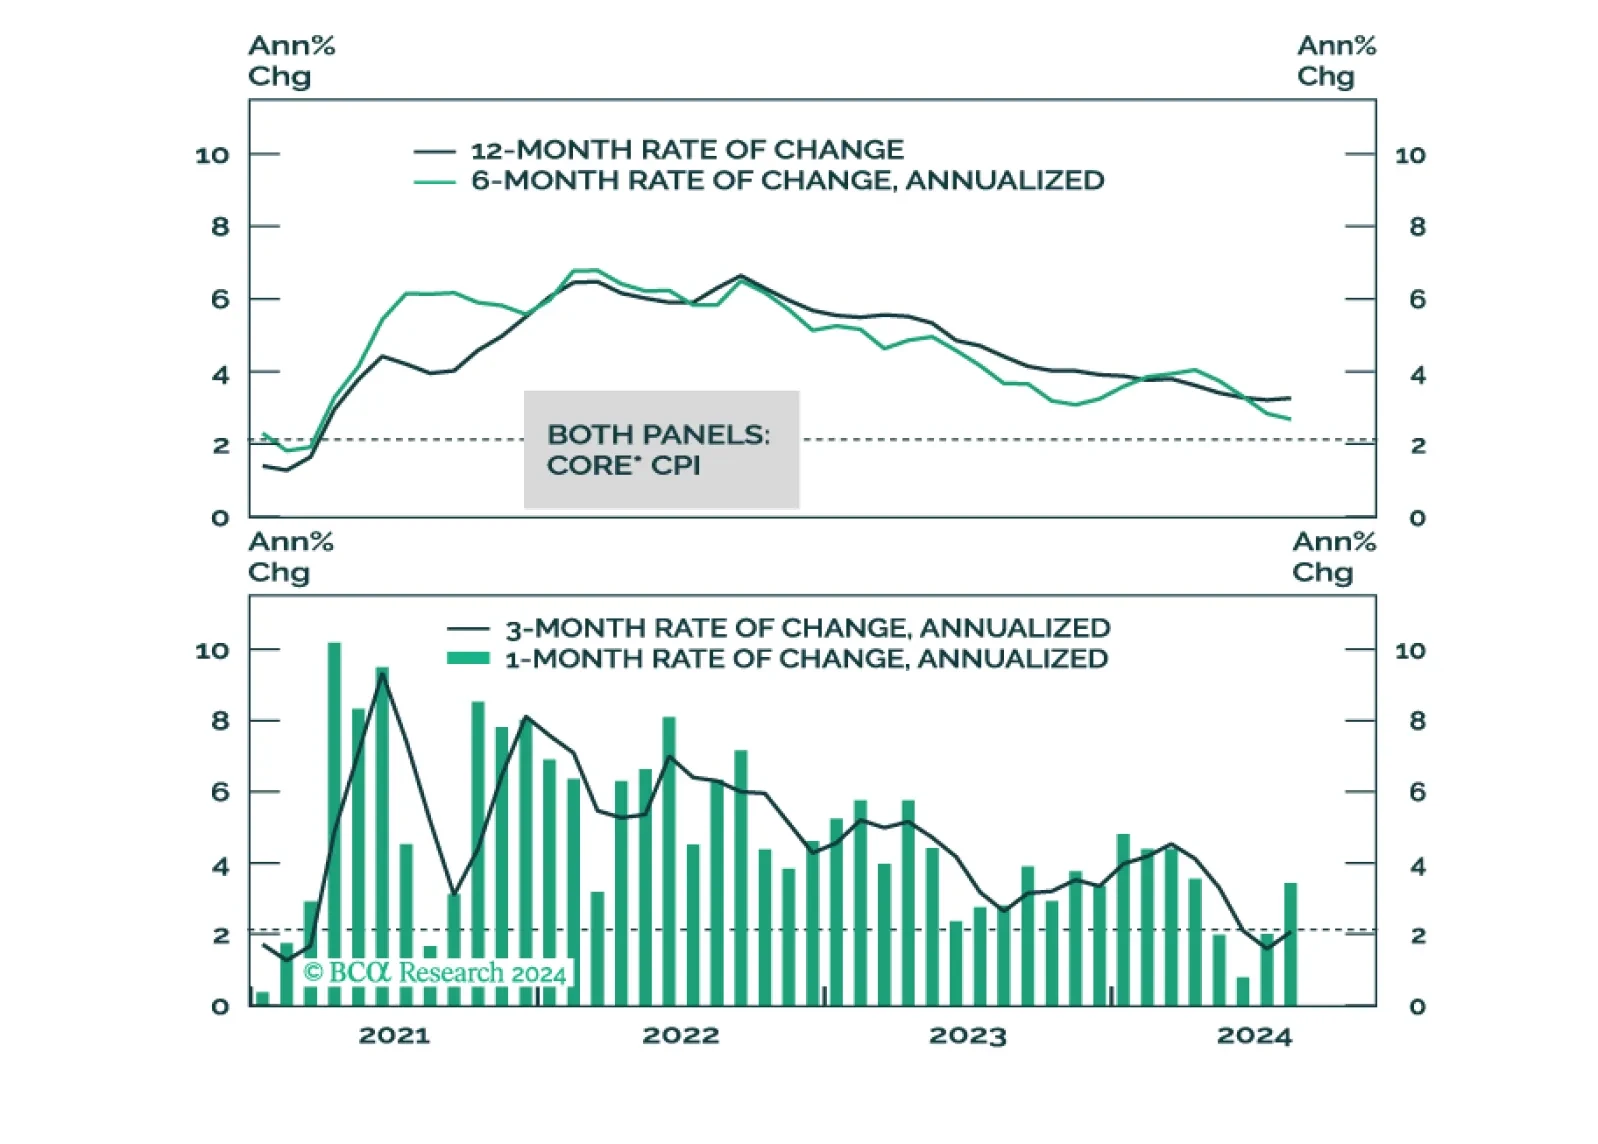
Our reaction to this morning’s CPI report and what it means for Fed policy.