Latest from BCA Research
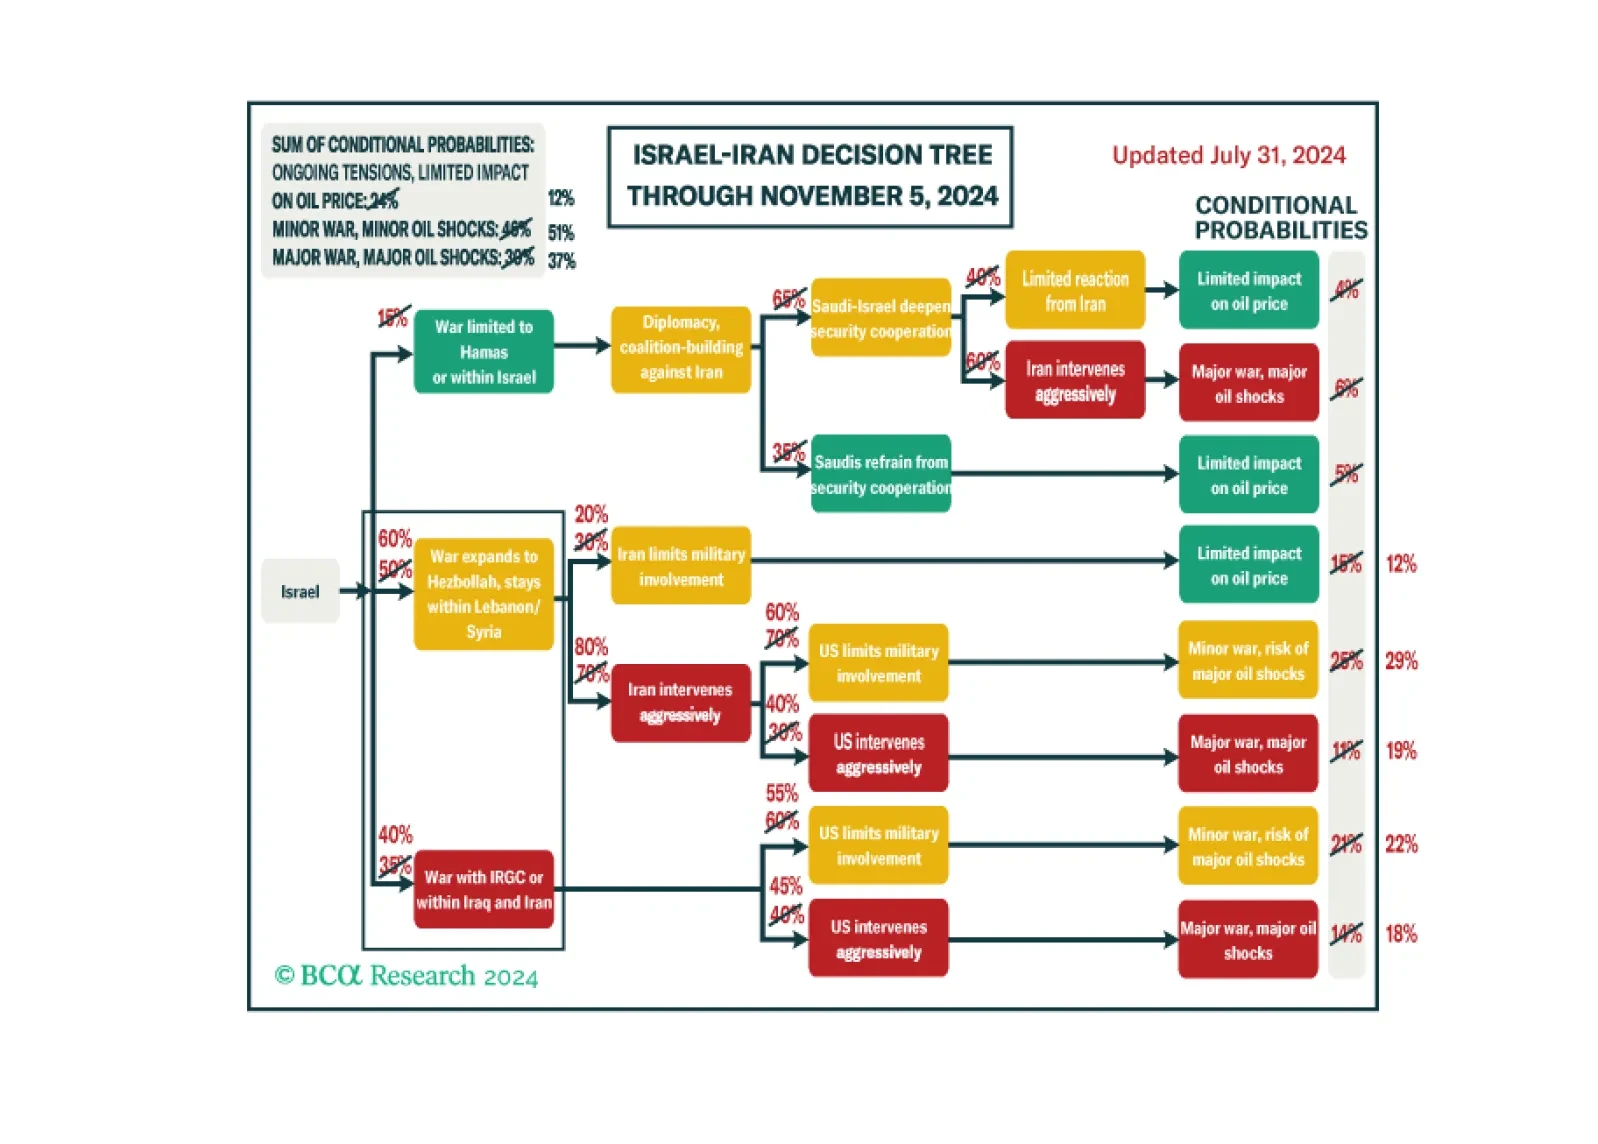
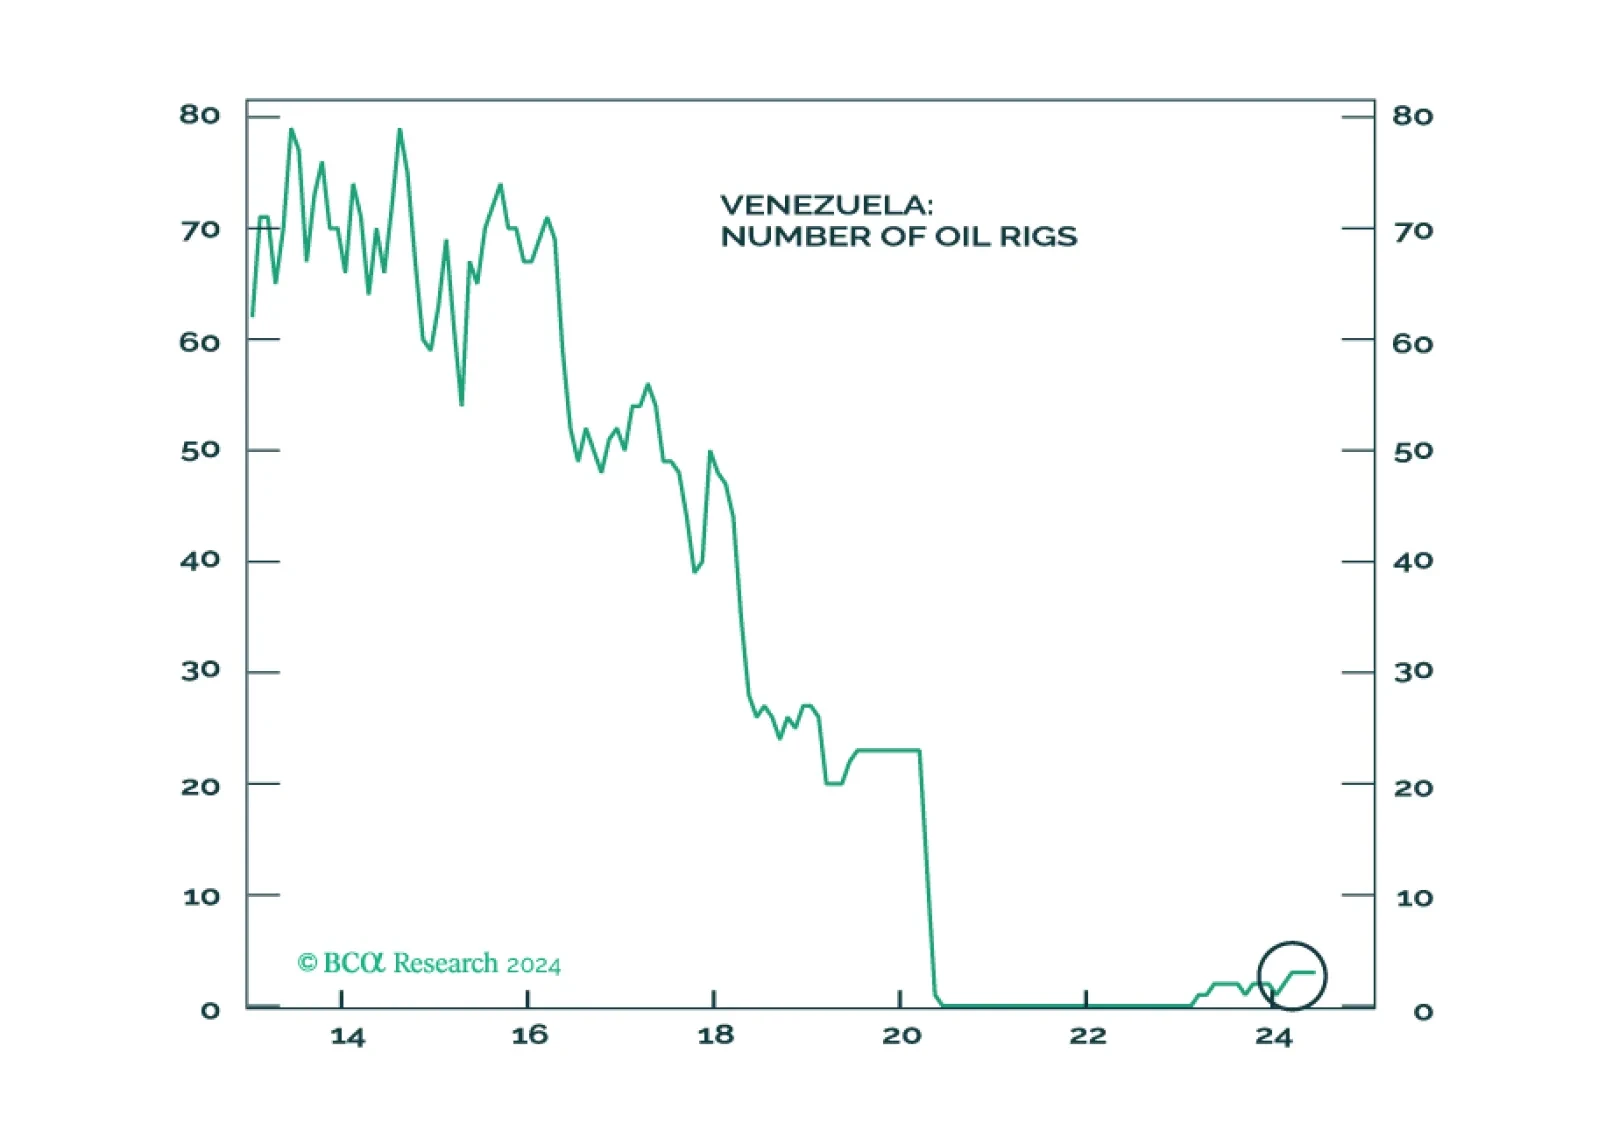
The war in the Middle East is expanding, upgrading our subjective odds of a major oil supply shock to 37% and underscoring our 60% odds of Republican victory in November. Volatility should spike again as investors contemplate the prospect of rising oil prices amid slowing US and global growth. Tactically investors should stay overweight energy stocks relative to other cyclicals and favor oil producers in the Americas rather than Middle East.

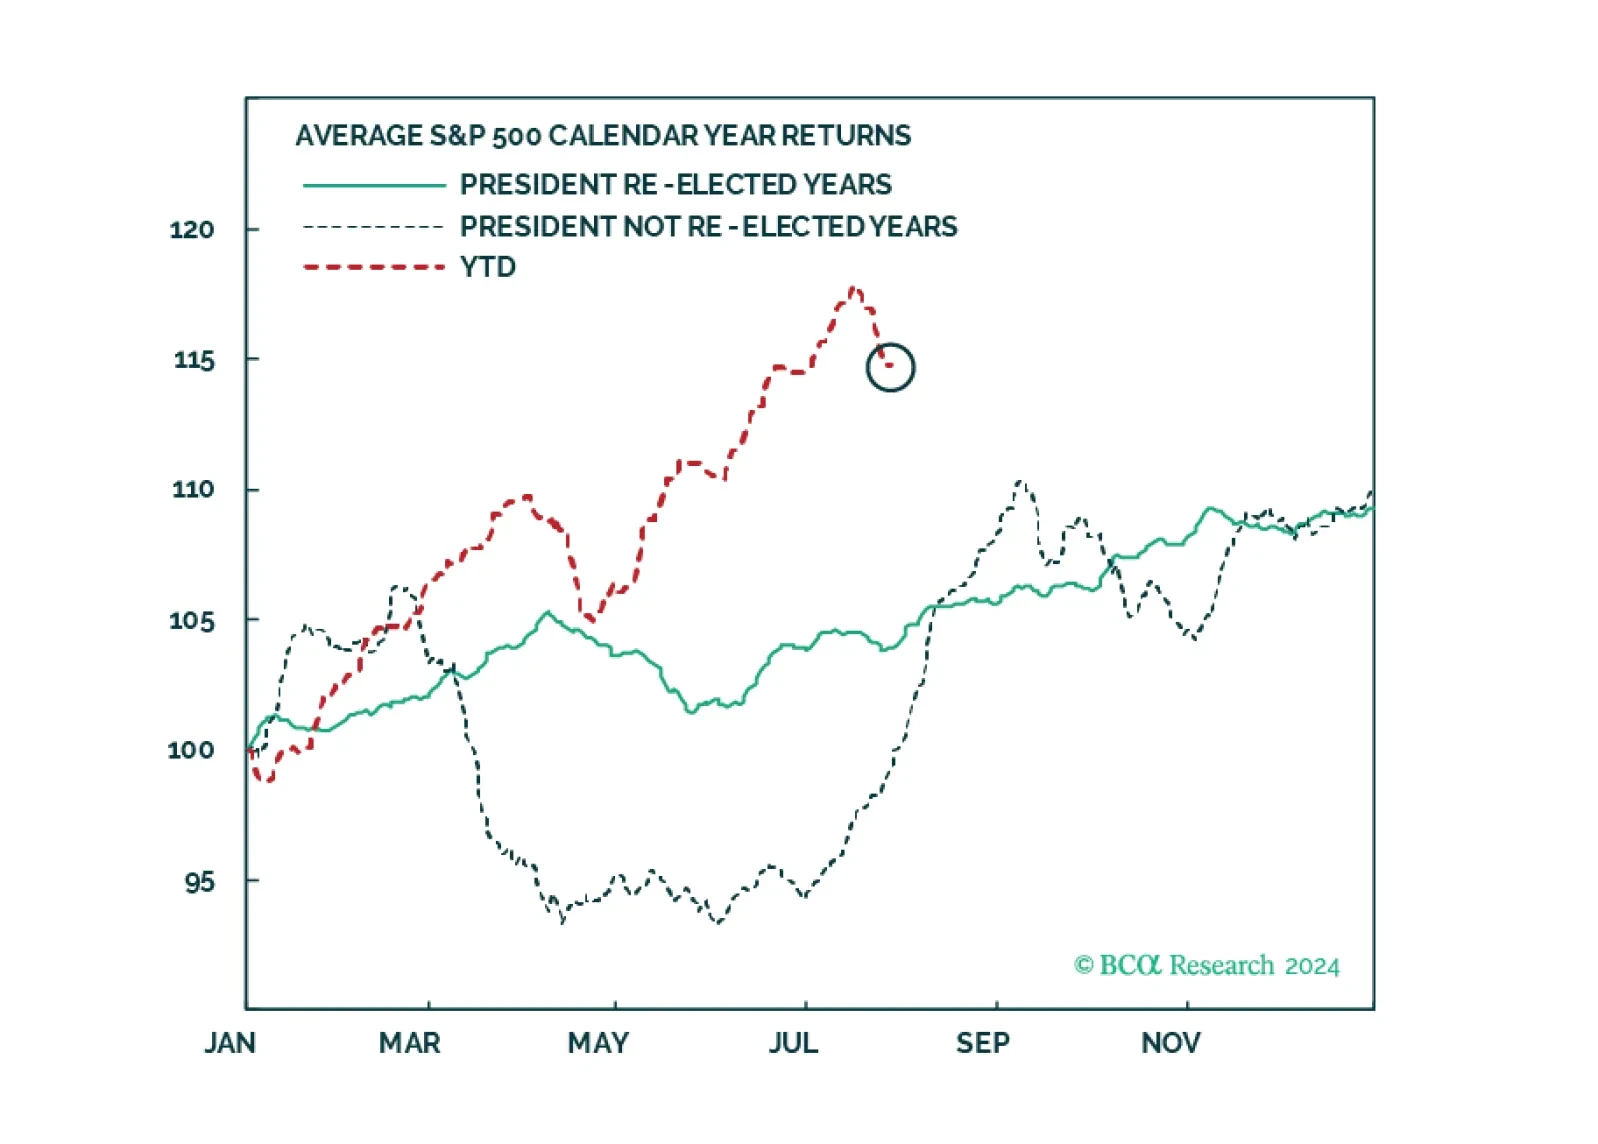
Republicans are favored but the election is still competitive. Equities, corporate credit, and cyclical sectors will fall until policy uncertainty is reduced.
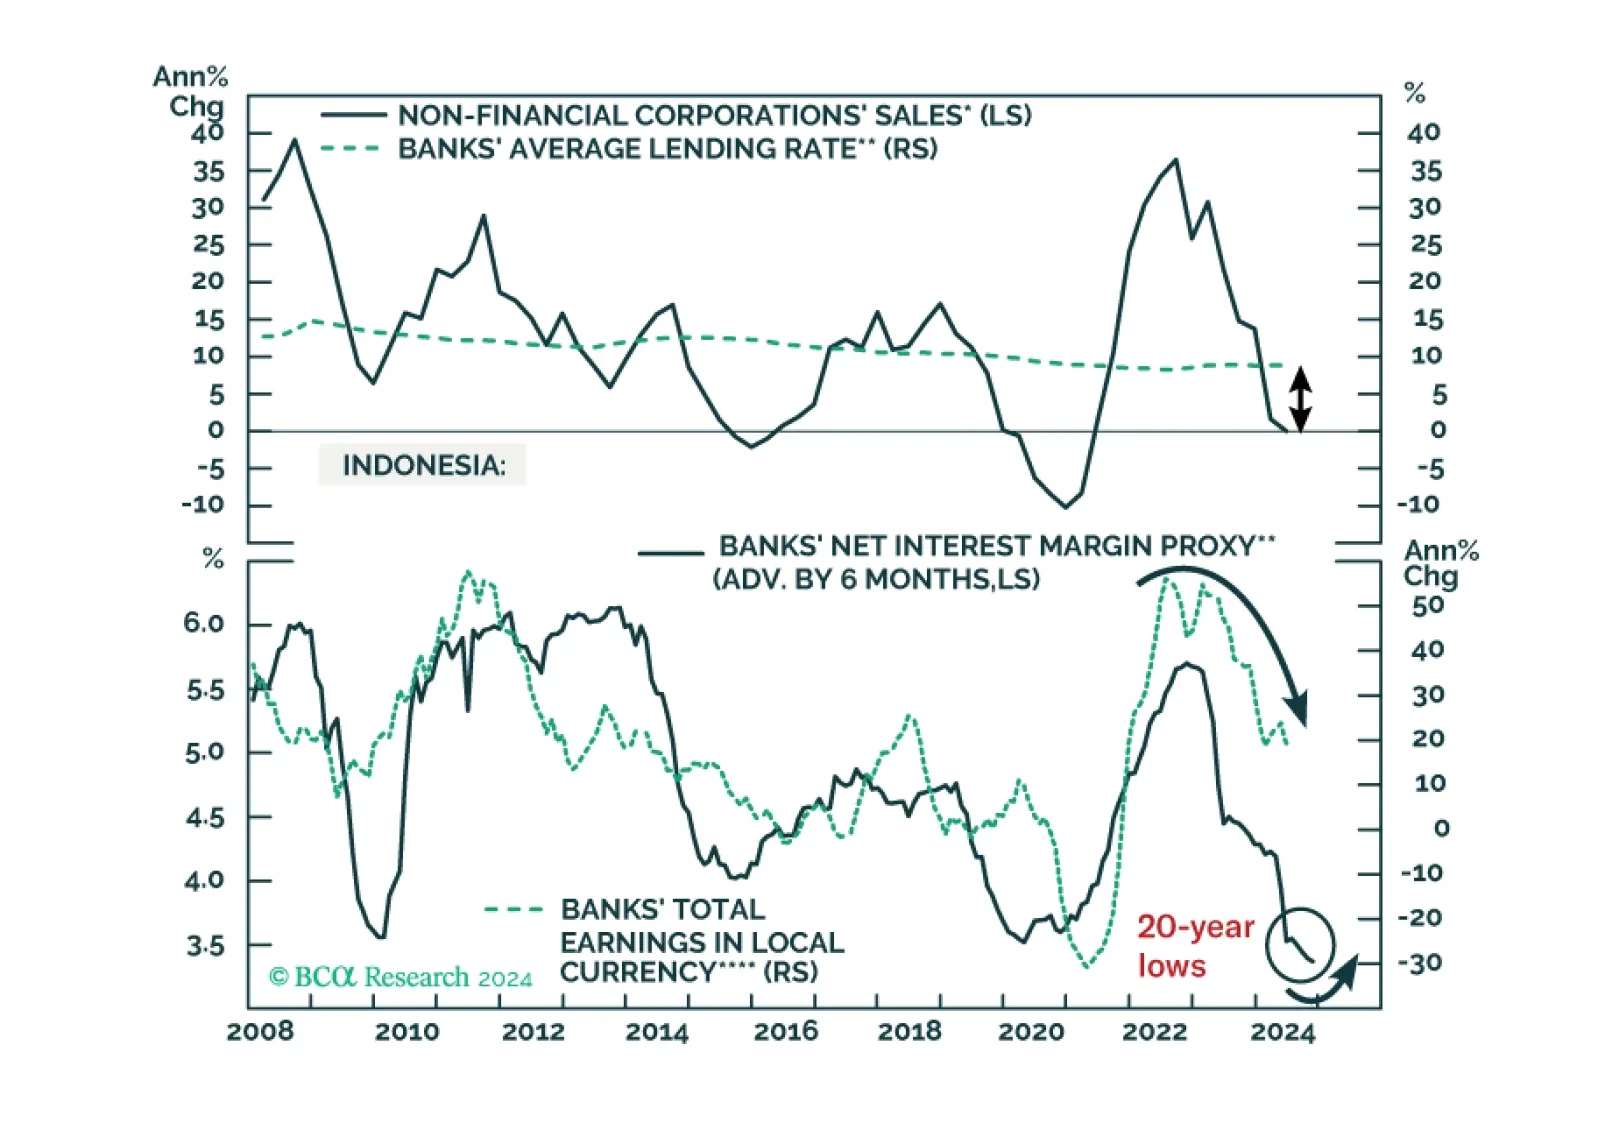
A major slowdown in nominal growth was behind Indonesia’s recent stock underperformance. Dedicated EM equity portfolios should upgrade Indonesian stocks from underweight to neutral. We also recommend a new relative trade: go long Indonesian banks / short EM banks.
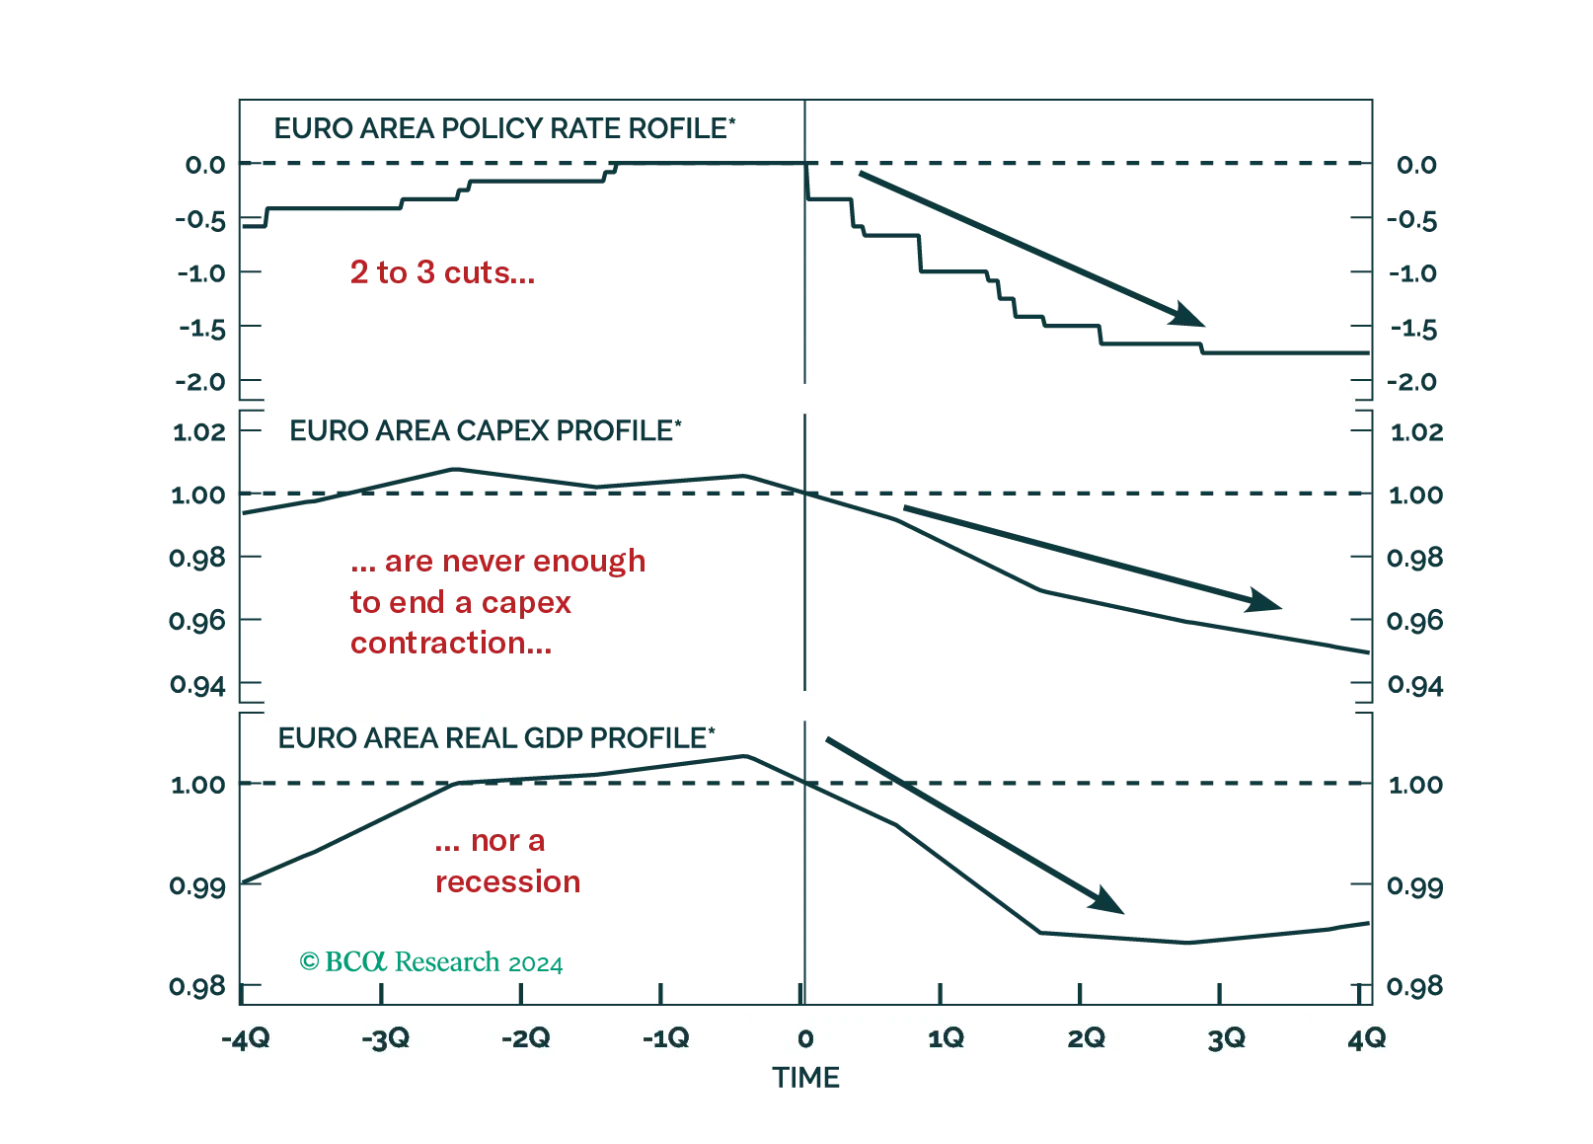
Investors hope that the ECB rate cuts priced into the curve will be sufficient to achieve a soft landing in Europe. History argues against this view, but will this time be different?

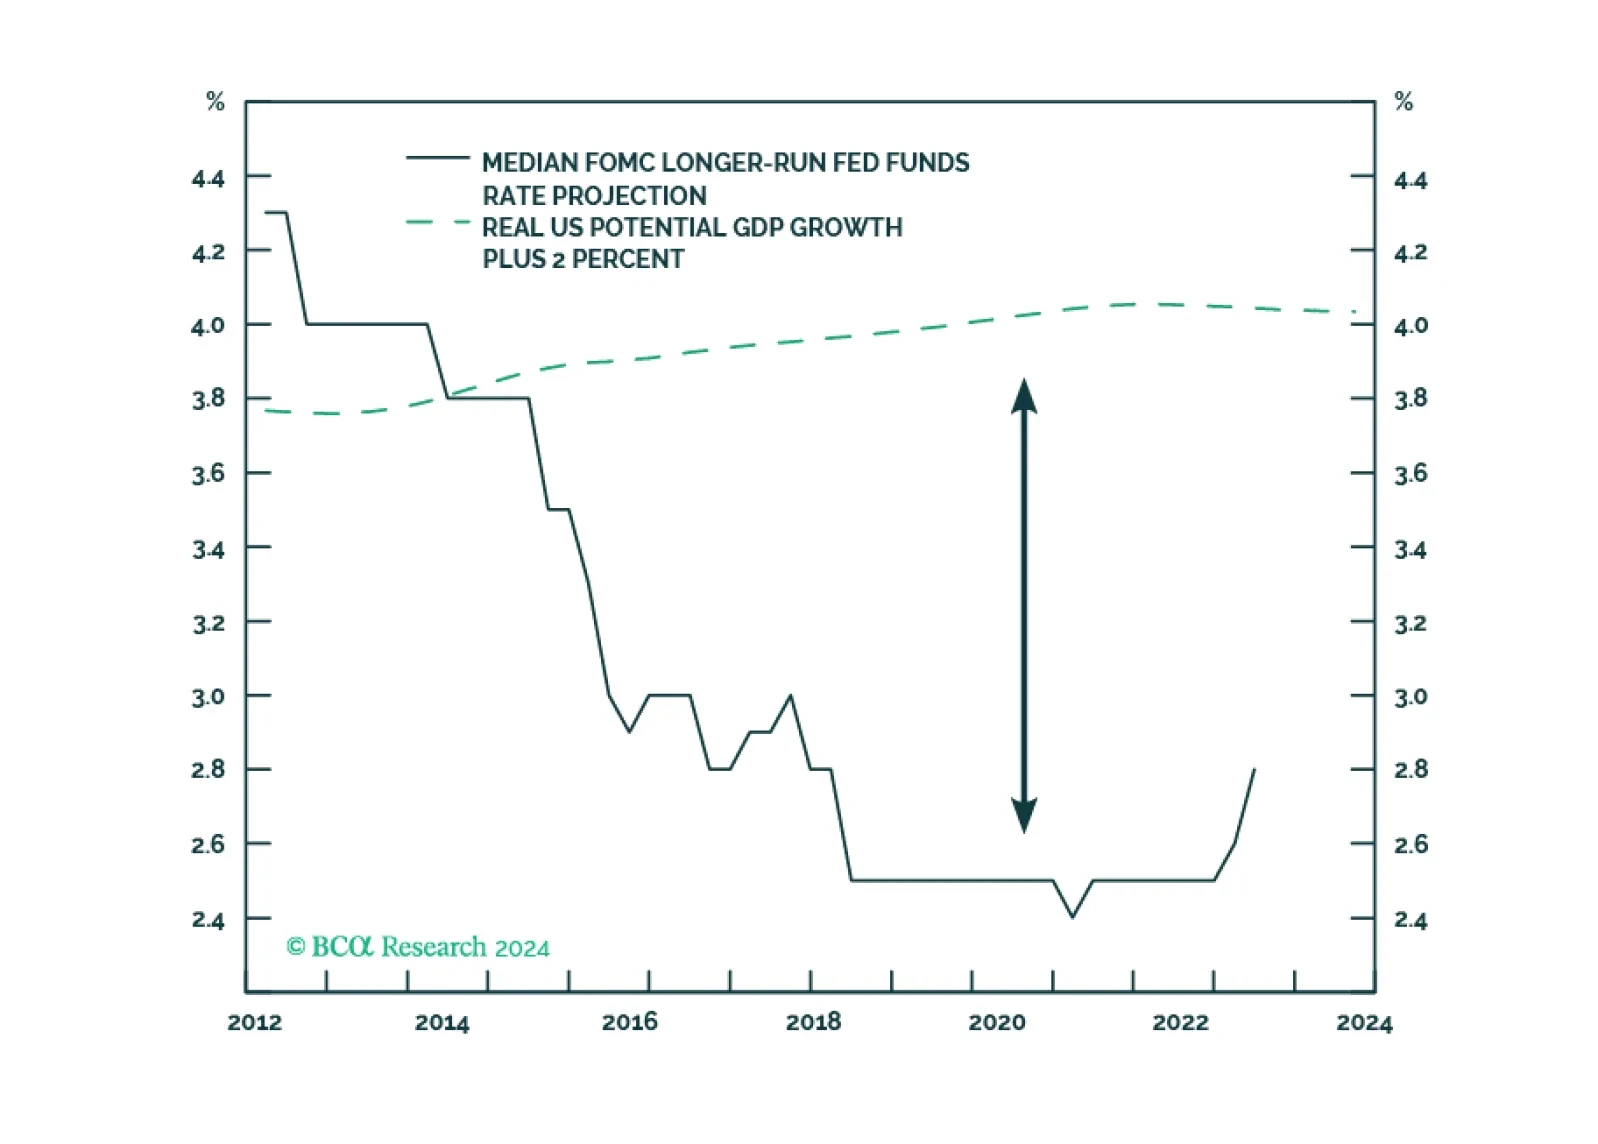
This report takes a look at bond and FX market technical indicators and calibrates the decision to increase portfolio duration and get long the US dollar.
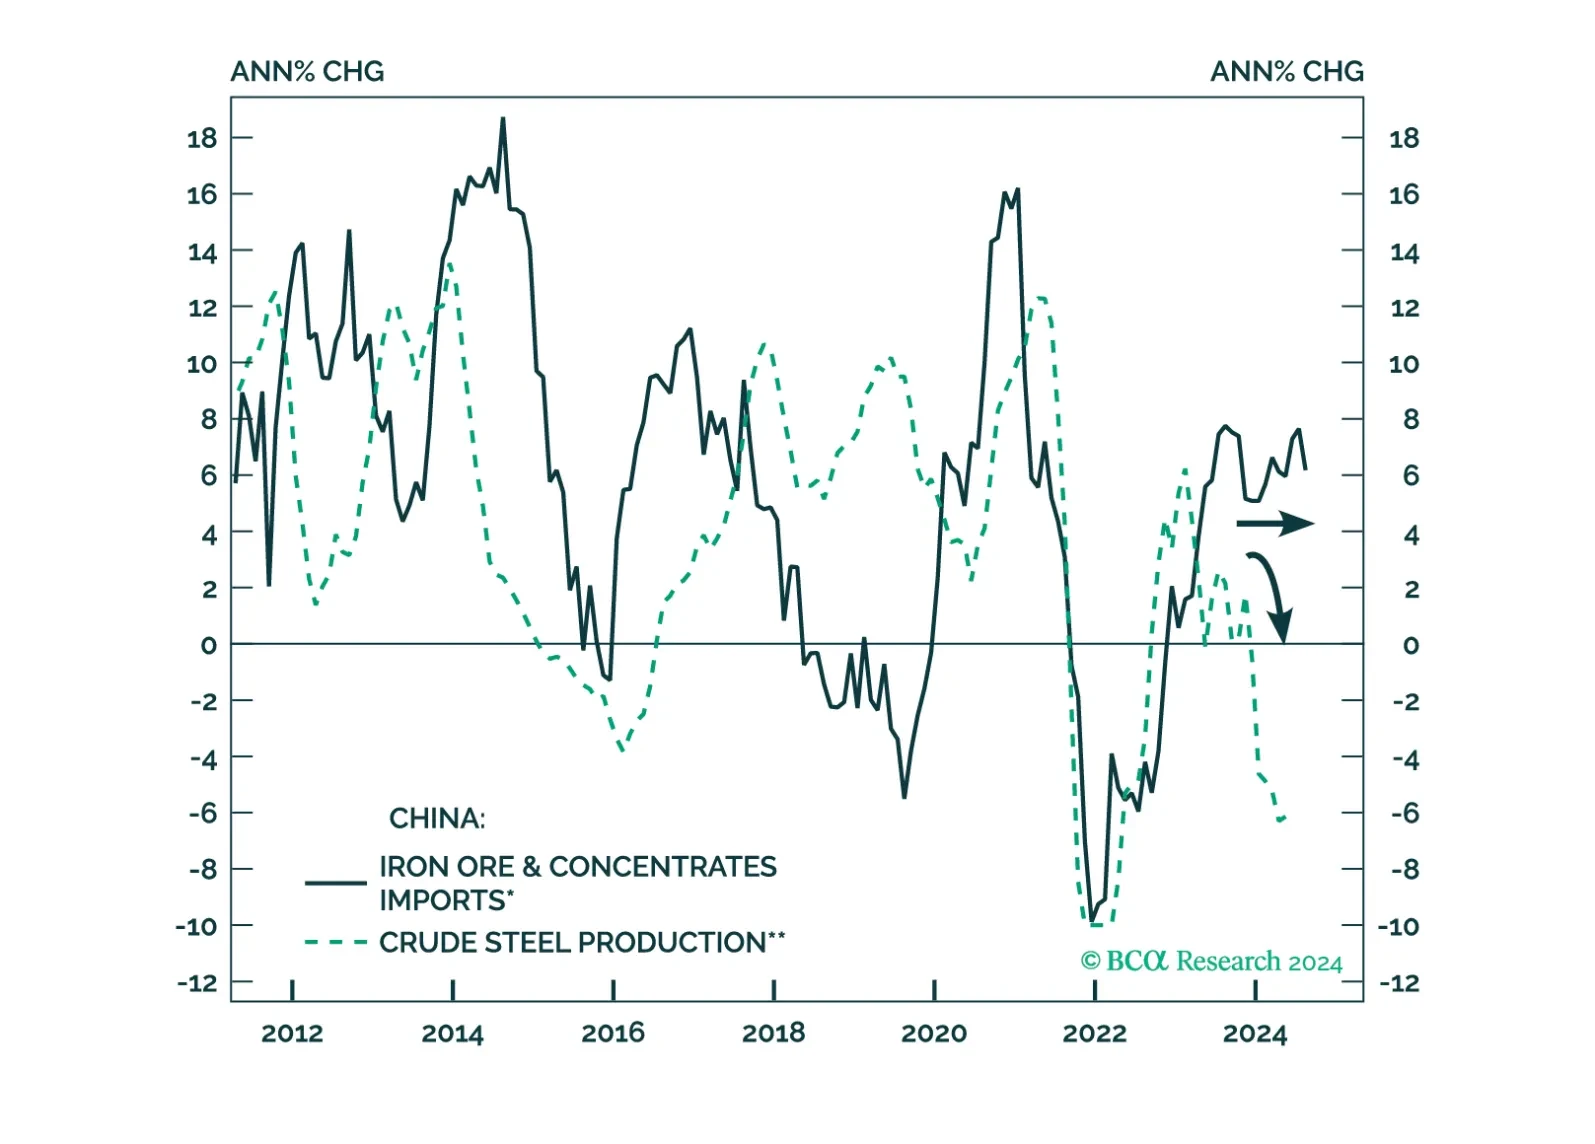
The absence of a catalyst that will boost Chinese steel demand dims the odds that iron ore and steel prices will recover over the coming six-to-nine months. Instead, we expect ferrous metals to face further downside into year-end.