Skip to main content

Latest from BCA Research
This month the BCA Sector Score upgraded Consumer Staples and Communication Services. In response, Energy finally fell out of the top spot. Also, the BCA Style Score continues to favor large cap growth. To give context to the global style tilts, we break down the factor long/short performance by region and suggest some screens.
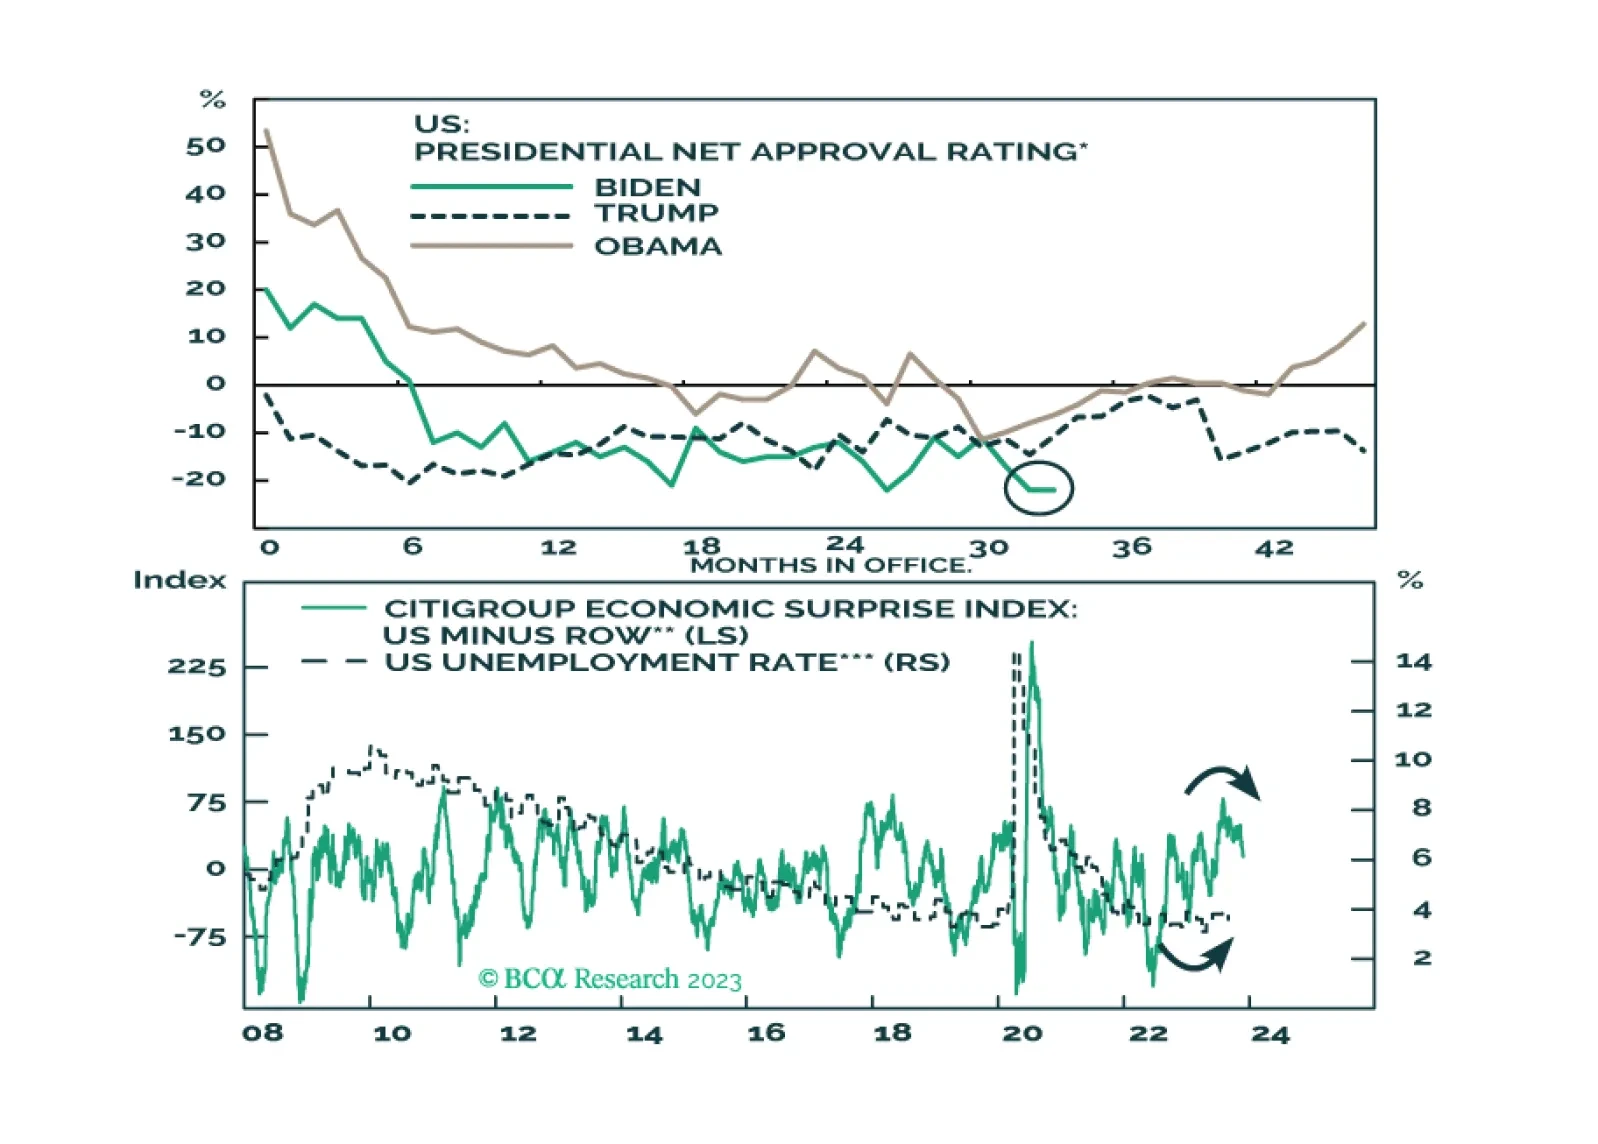
Global instability will continue in 2024 – whatever happens afterward. Slowing economies will exacerbate already high geopolitical risk and policy uncertainty stemming from the US election and foreign challenges to US leadership. Overweight government bonds, defensive sectors, the Americas versus other regions, aerospace/defense stocks, and cyber-security stocks.
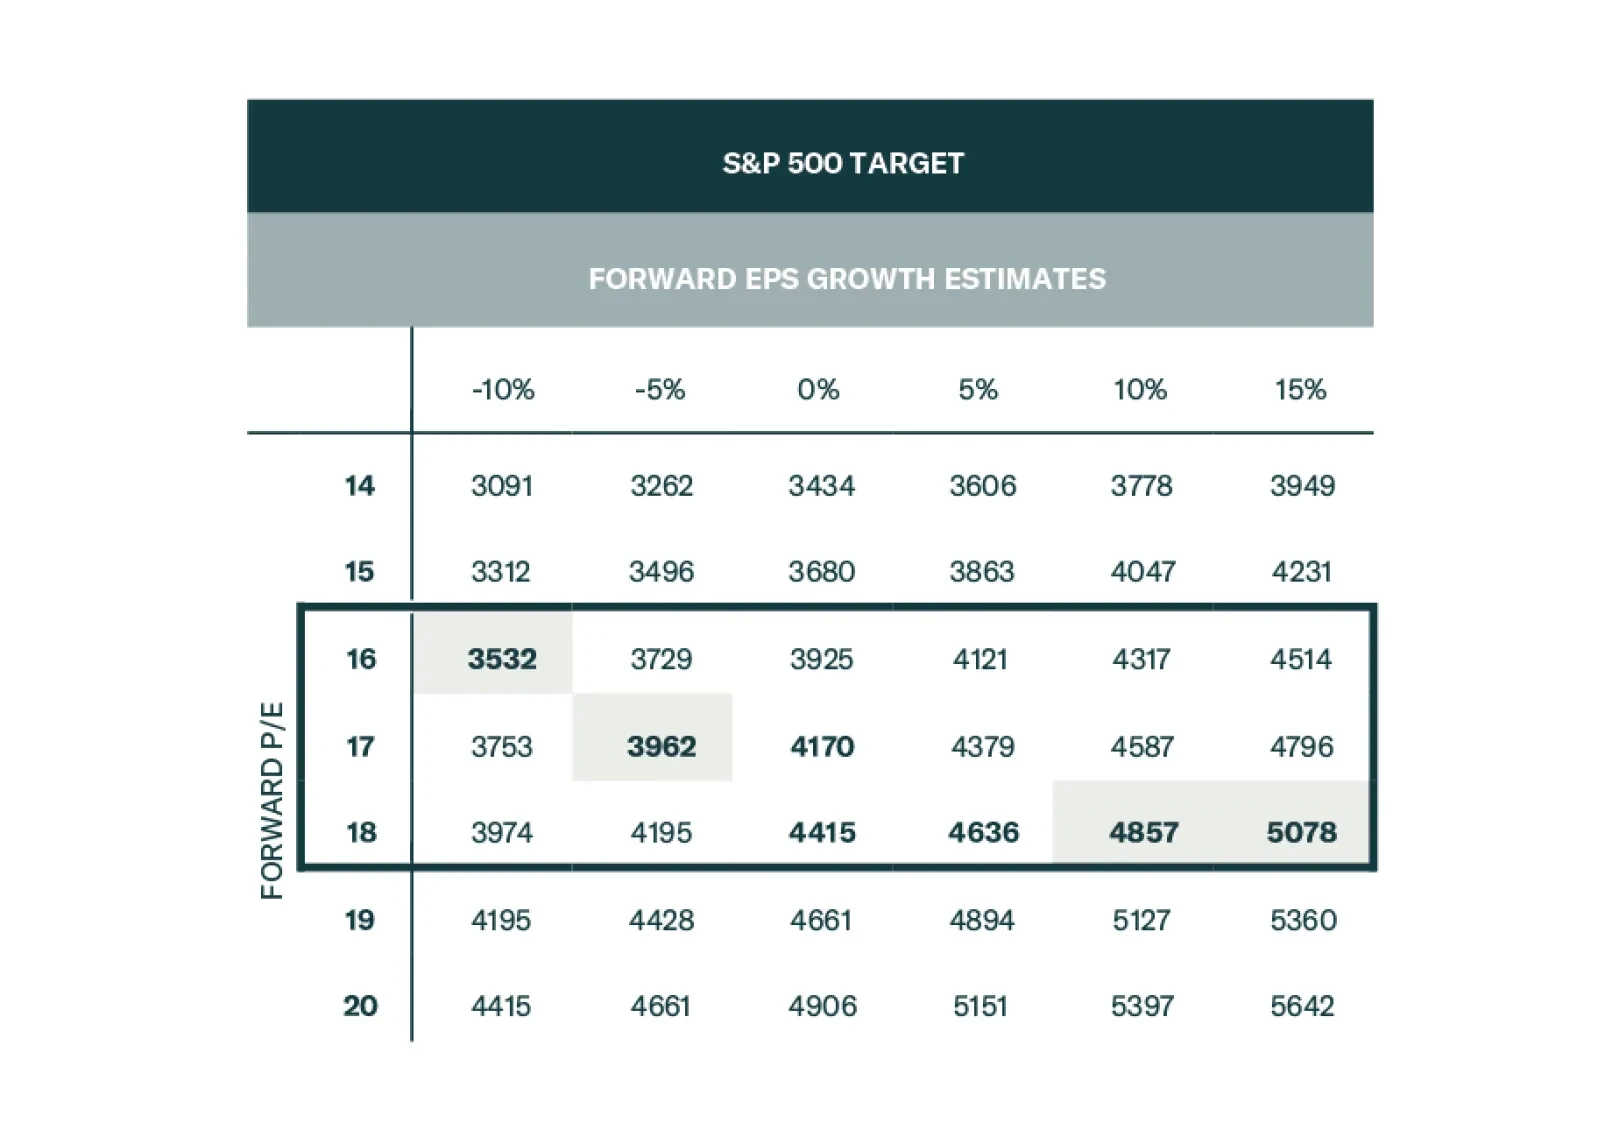
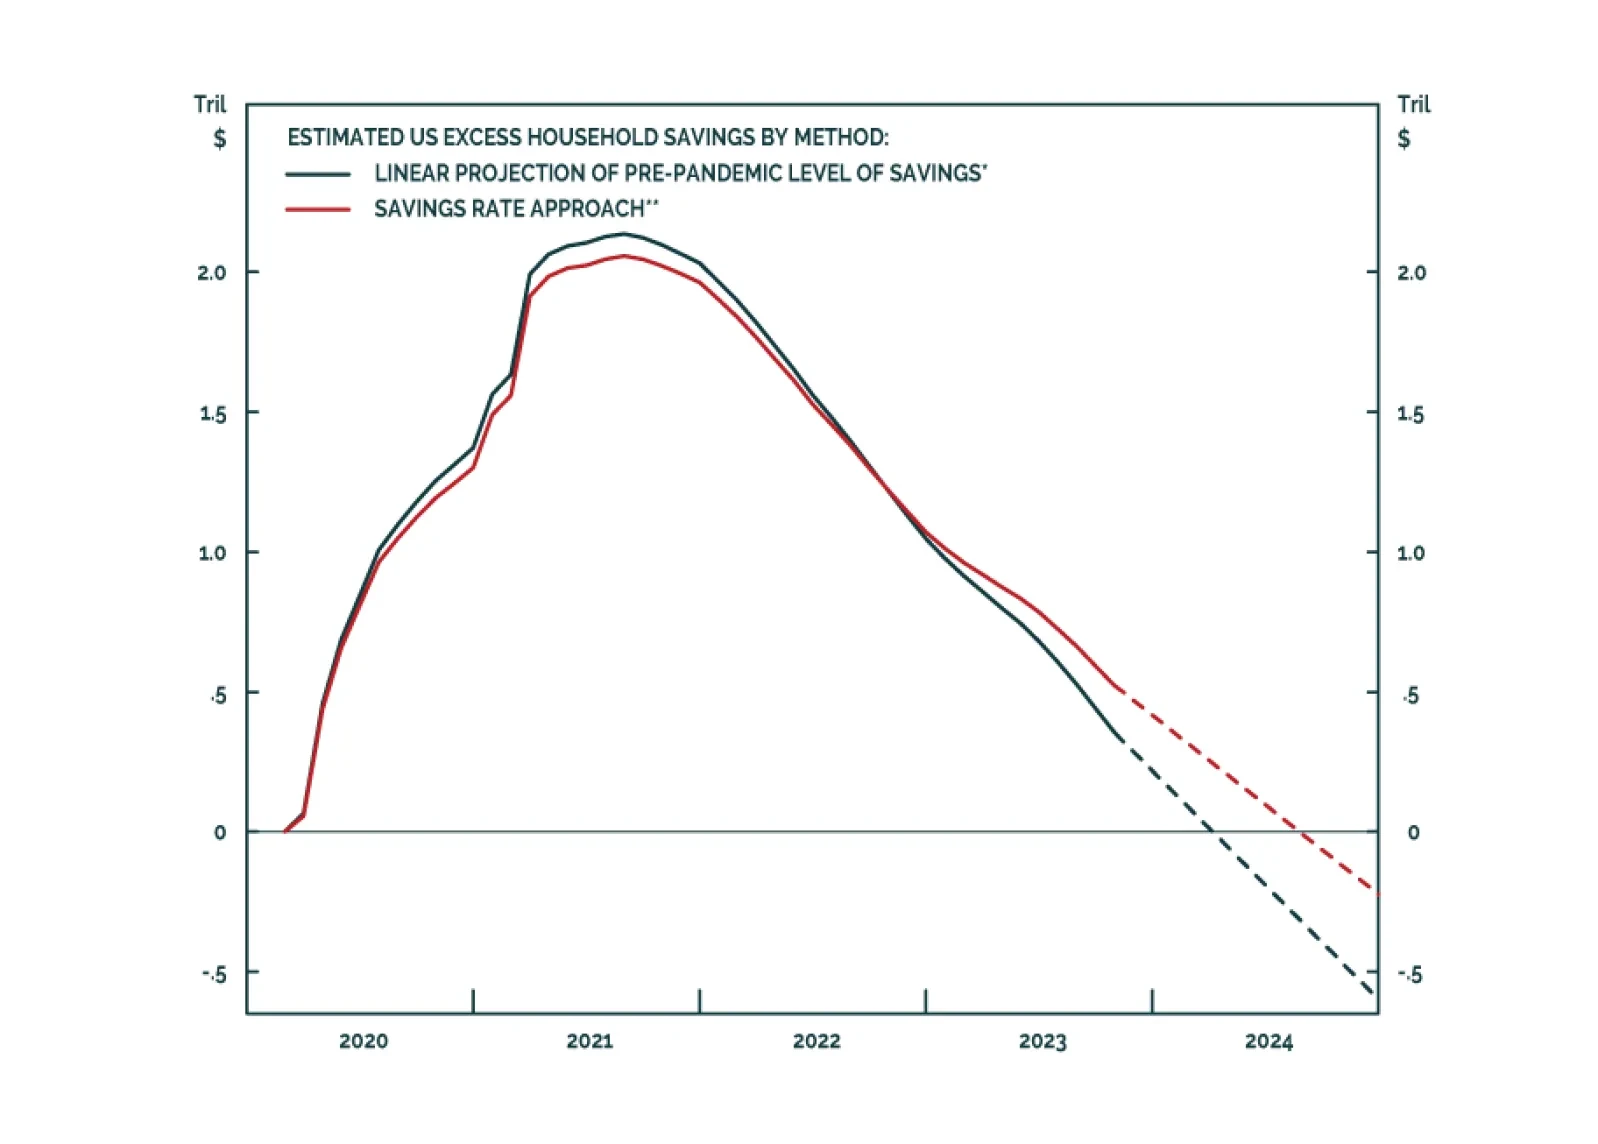
Special Report We expect the US economy to slow and potentially downshift into a recession sometime in 2024, as tighter monetary policy weighs on consumers and businesses. In addition, (geo)political tensions may increase market volatility. The risk/return for US equities is unfavorable. We recommend that our clients reduce portfolio beta and increase allocations to defensives and quality growth.
Our Portfolio Allocation Summary for December 2023.
Special Report We enter 2024 as we were across the last four months of 2023, tactically equal weight across the board until the S&P 500 rally is complete and we gain a better entry point for underweighting equities and overweighting fixed income.
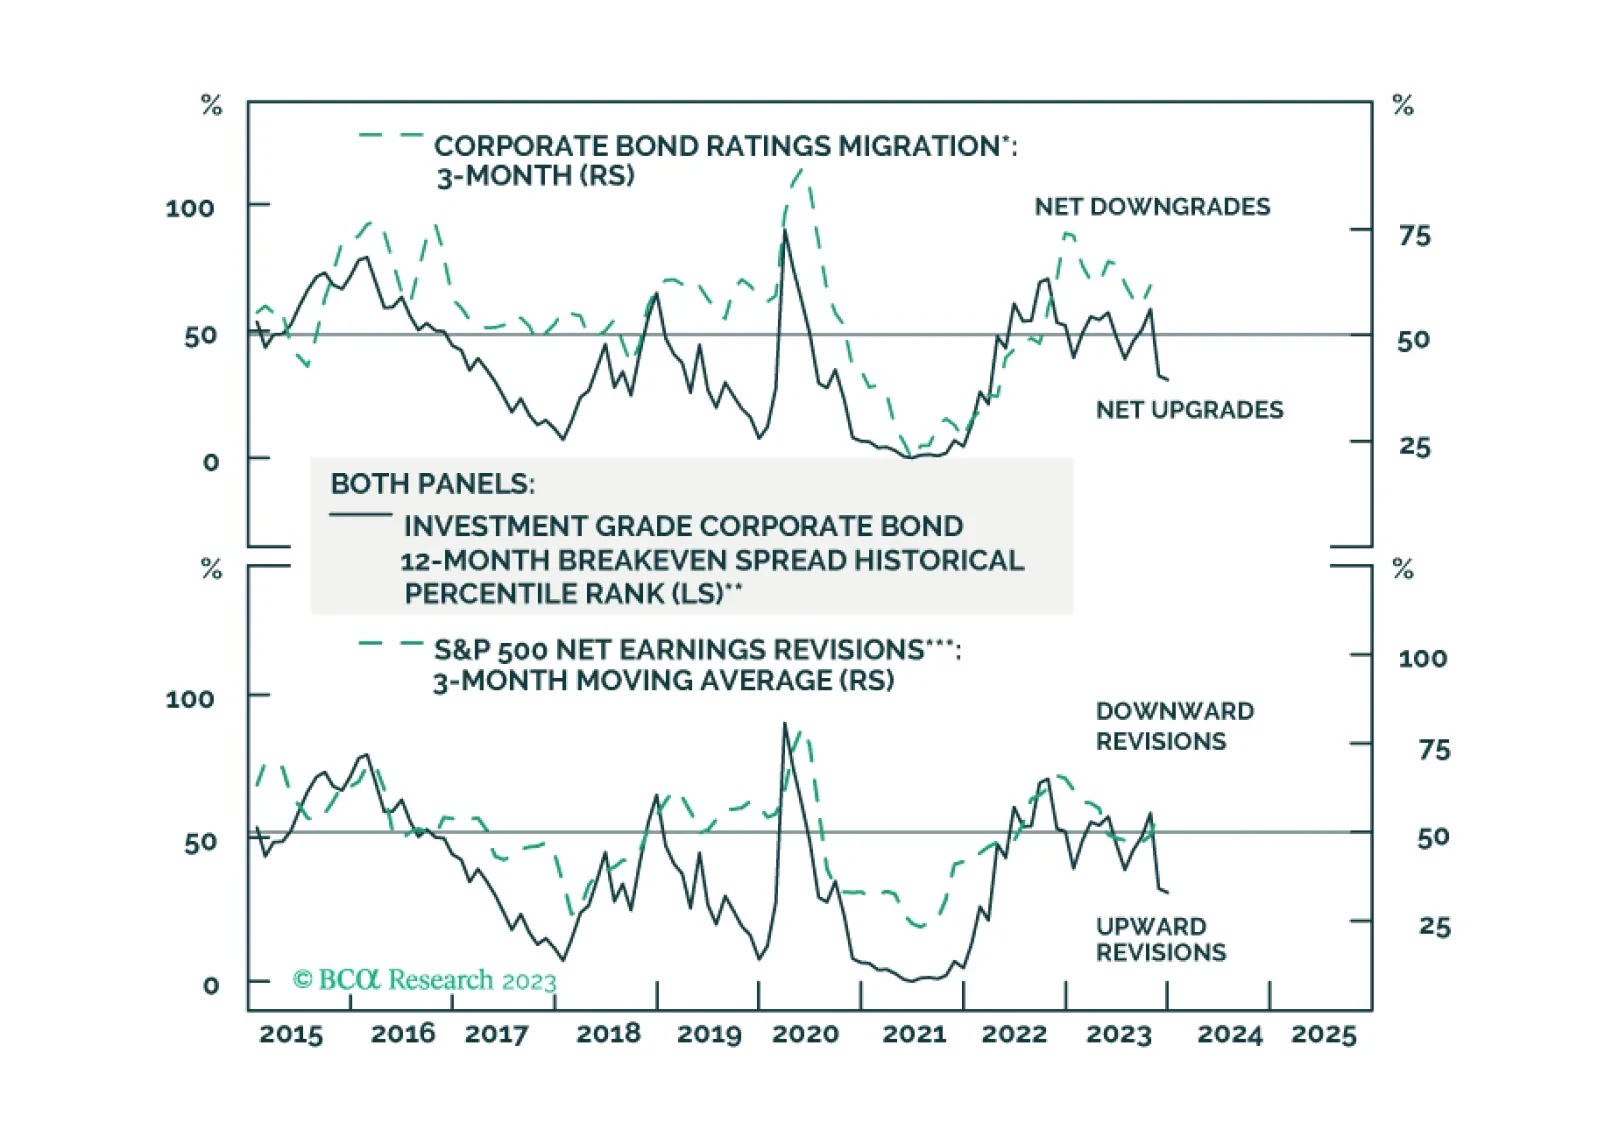
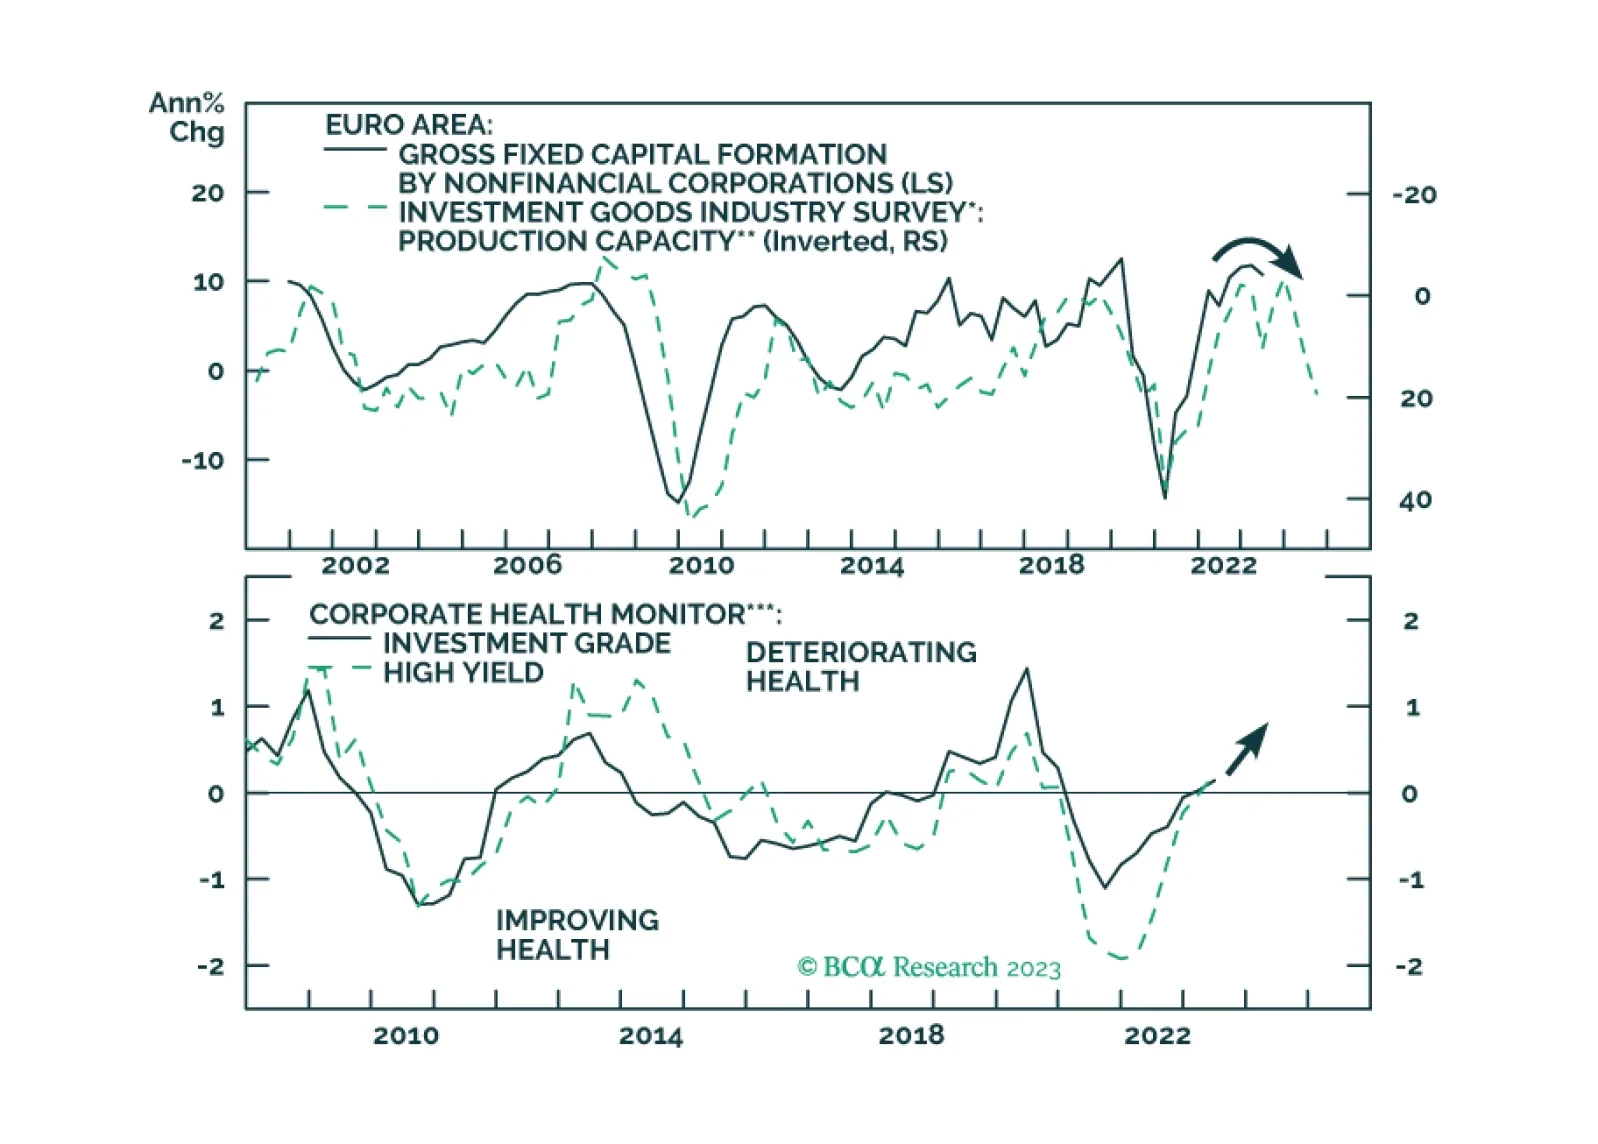
The recent uptick in European economic data will not last beyond the next six months. How will European corporate credit perform in this context?
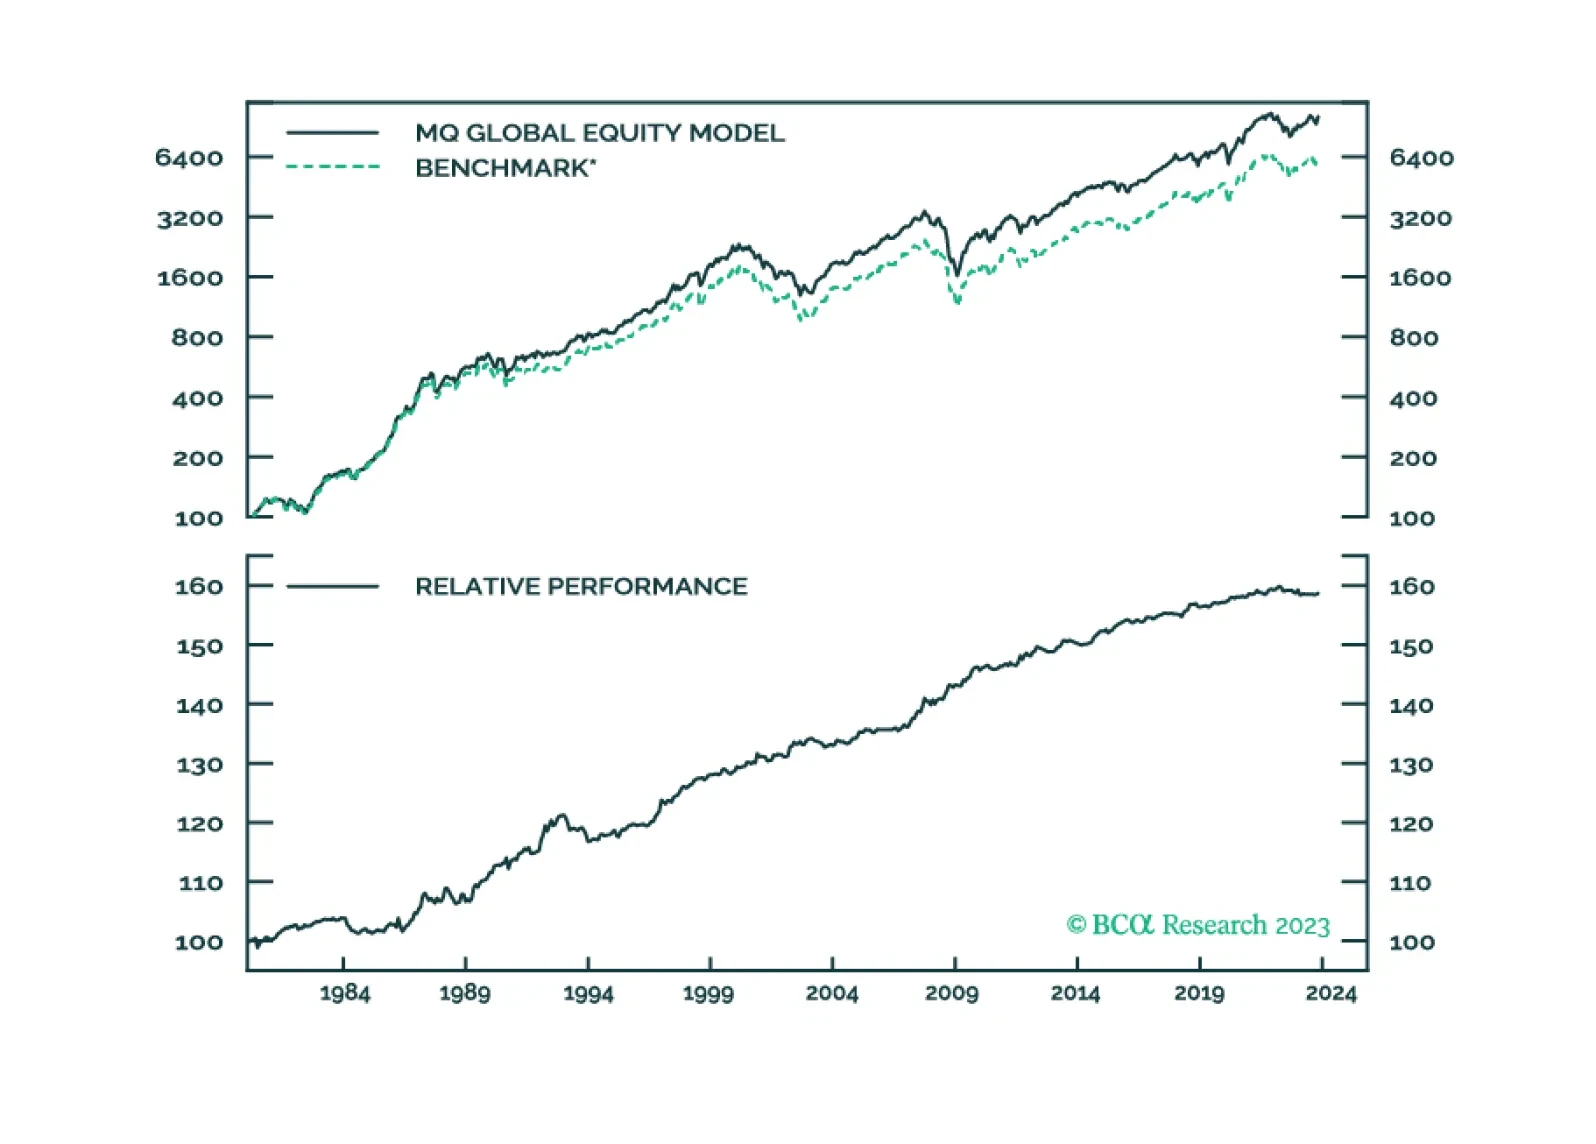
MacroQuant is overweight bonds and cash and underweight equities.
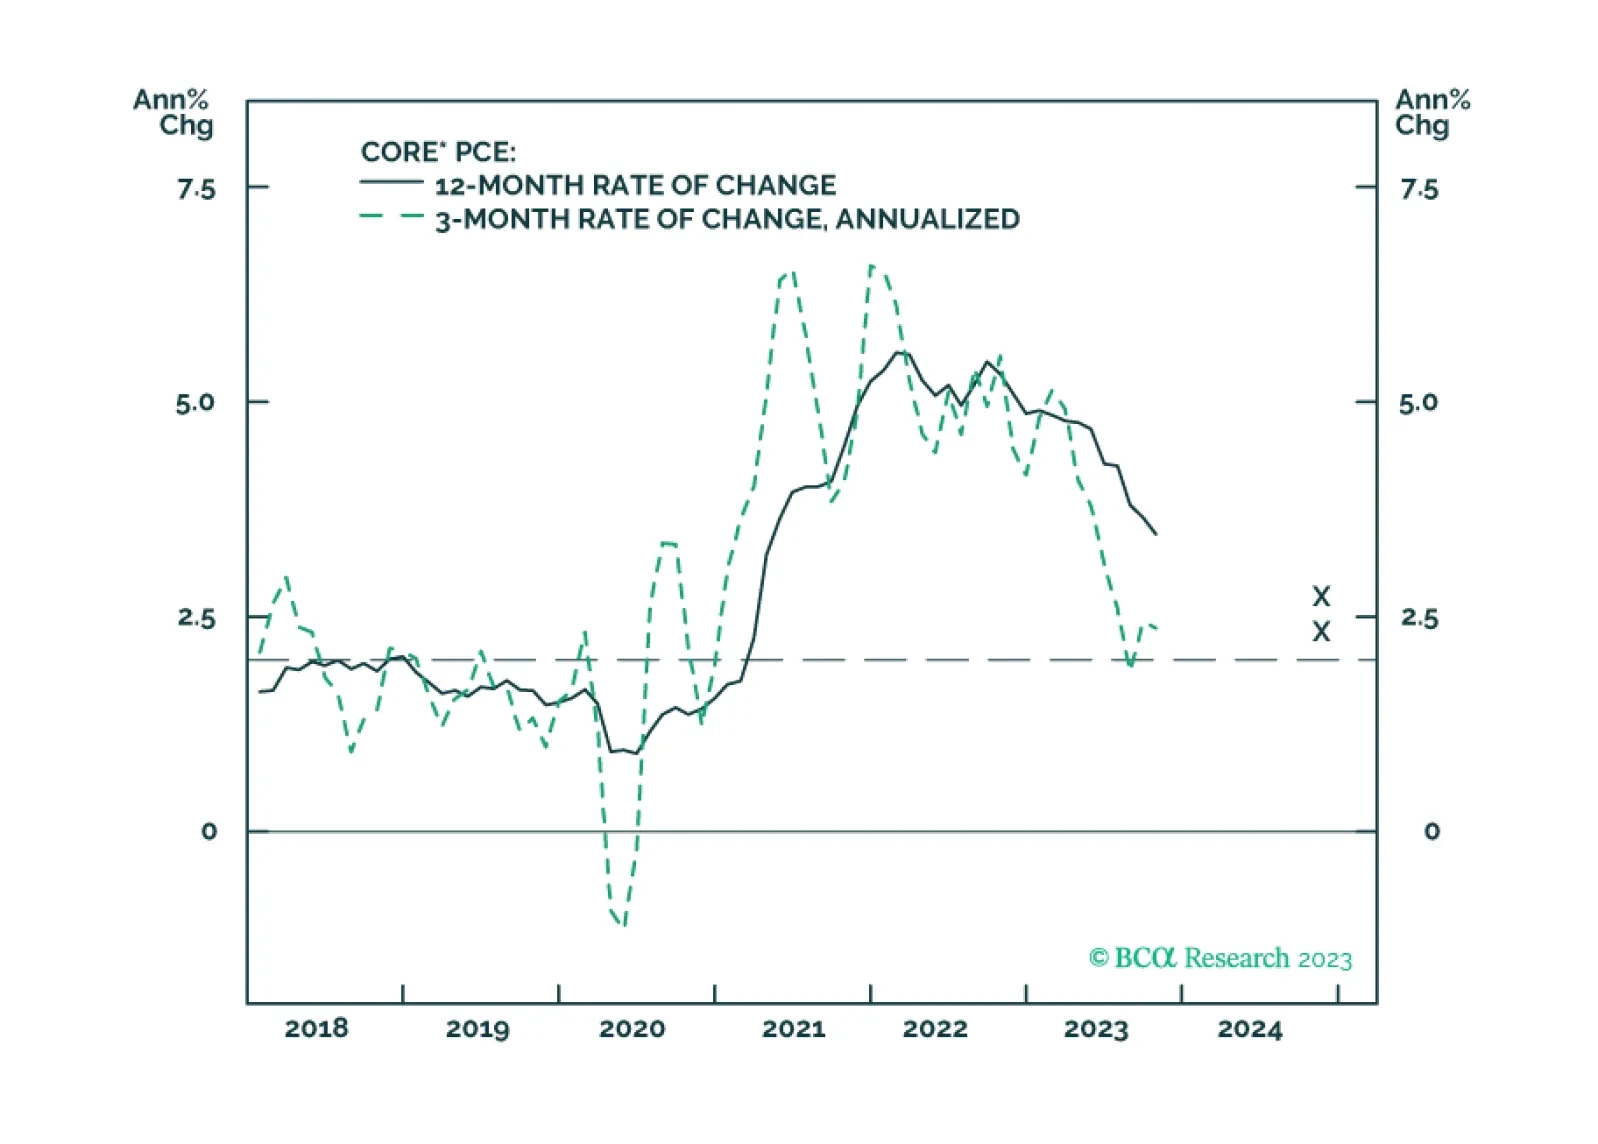
Treasury yields will sketch out a range between now and Q1 2024, with the upside determined by inflation and the downside determined by labor markets.
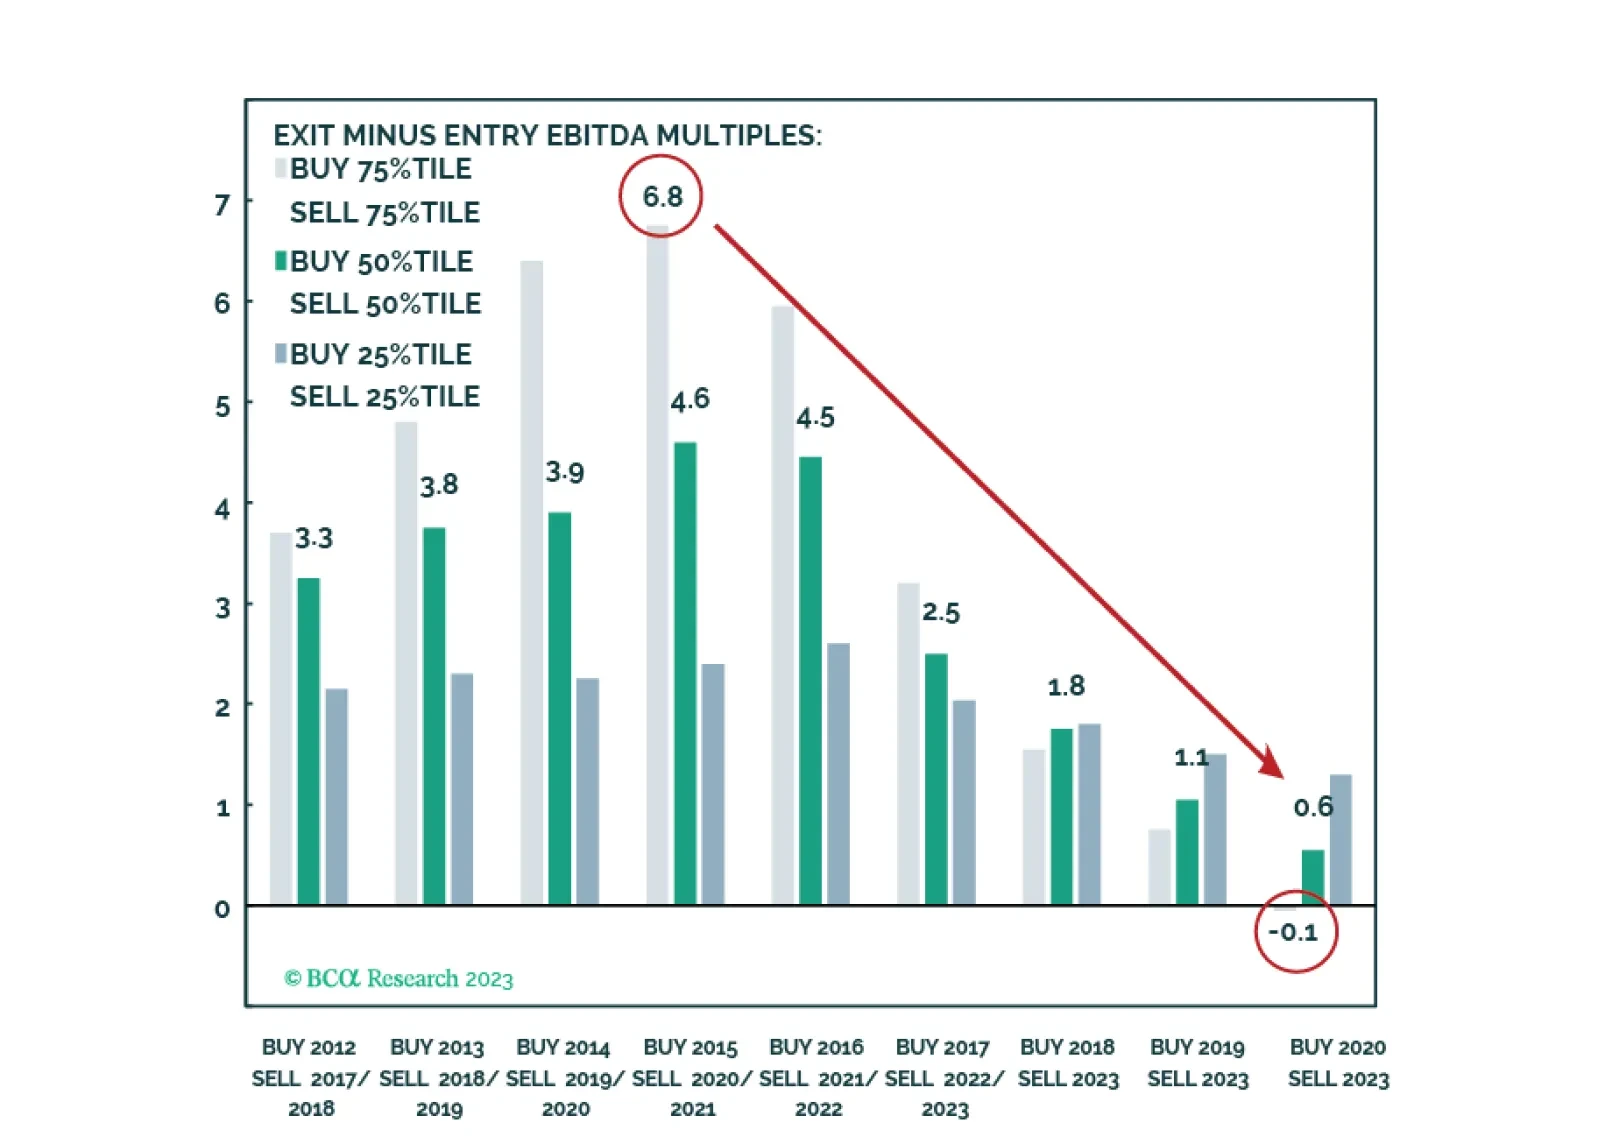
Special Report The next dollar into Private Equity carries more time and opportunity cost risk. We do not see a high risk of permanent capital loss for the next vintages; existing vintages we do. While our primary focus revolves around the next dollar, it is valuable to comprehend the risks associated with current investments made through yesterday's allocations. In this report we delve into risks pertaining to dollars invested in the past and those earmarked for the future, with a special emphasis on Buyouts.
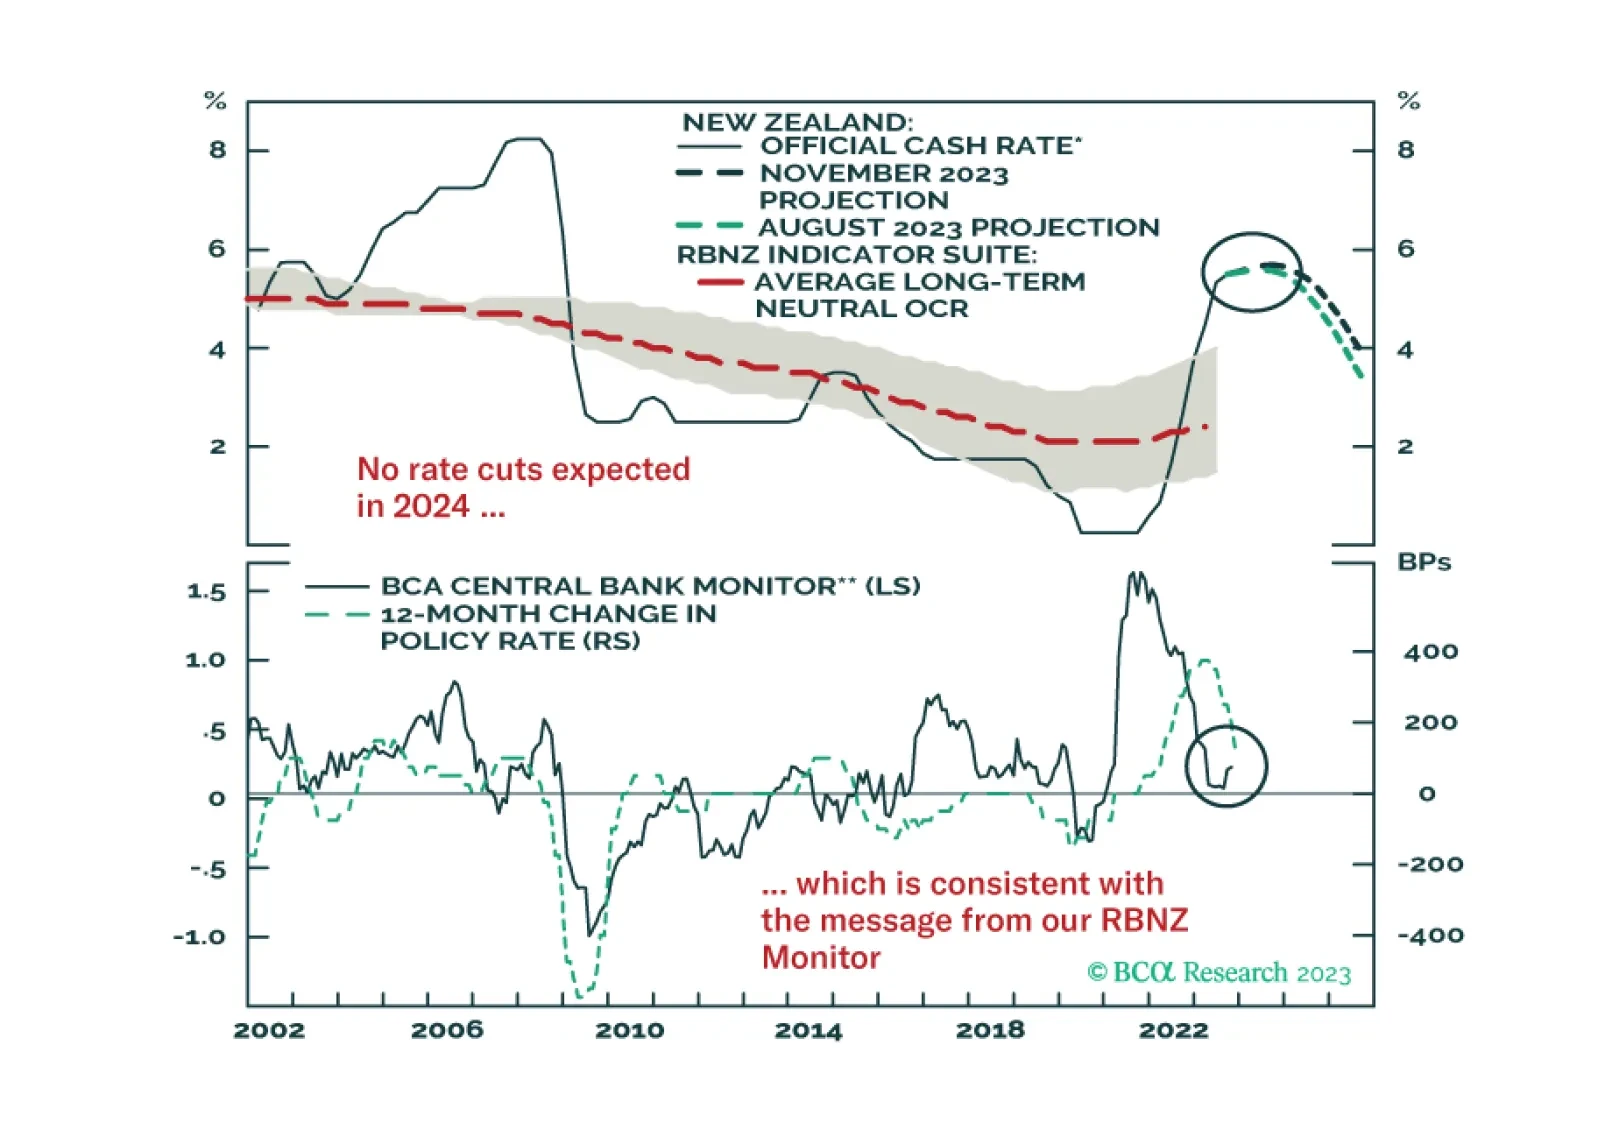
In this Insight, we discuss the outlook for monetary policy in New Zealand after this week’s RBNZ policy meeting, and introduce related fixed income and currency trade ideas.